Oil and Gas Sector Update : Crude Compass: Oil Supply Swells, Diesel Stays Tight Choice Institutional Equities
Developments over the week:
* China resumed crude inventory accumulation in October, with imports and domestic production exceeding refinery throughput by ~490 kbd, marking the first estimated stock build since July. Crude imports reached a seven-month high of 9.88 mbd, while refinery throughput declined 8.1% YoY. Diesel exports declined to ~313kbpd from 500kbd in September, reflecting Beijing’s stringent export approvals and prioritisation of domestic supply. Commercial diesel inventories declined to ~83 million barrels, their lowest level since 2011.
* Russian seaborne crude exports rose to 3.9 mbd in the four weeks ended 15 November, increasing 280kbd w-o-w to their highest level since late July, as Ukrainian attacks forced refiners to divert unprocessed crude into export markets. Weekly shipments surged 950kbd to 4.32 mbd, the highest since June. Ukraine has reportedly targeted 13 Russian refineries since early November, further constraining domestic refining throughput. Shipments to Asian buyers, predominantly India and China, increased to 3.72 mb/d from 3.42 mb/d, while Mediterranean flows declined to 180,000 bpd. Despite higher export volumes, Russia’s four-week average crude export revenues fell to a seven-week low of USD 2.45 Bn per week, reflecting weaker Urals prices. * US crude and refined-product stocks registered stronger-than-anticipated builds during the week ended 13 November, suggesting some moderation in near-term supply tightness. As per the EIA report released on 18 November, commercial crude stocks expanded by 3.4 million barrels to 417.8 million barrels, while gasoline and distillate inventories increased by 5.2 million barrels and 1.6 million barrels, respectively. Overall commercial petroleum inventories rose by ~9.2 million barrels. Refinery utilisation remained elevated at 95.7%, despite crude processing declining by 129 kbd w-ow- to 16.9 mbd. Nevertheless, crude and distillate inventories remained ~3% and ~7% below their respective five-year seasonal averages.
Our view:
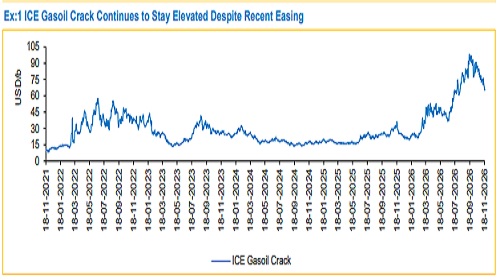
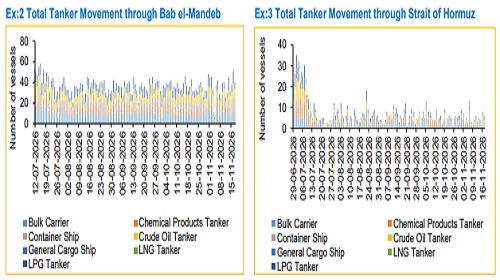
* We believe diesel cracks will remain elevated, given persistently depleted product inventories and constrained global refining throughput. With an estimated ~45% of Russian refining capacity disrupted, restricted oil product flows through the Strait of Hormuz and Chinese diesel exports declining despite spare refining capacity, incremental diesel supply remains constrained. Importantly, China's historically low diesel inventories and US distillate stocks remaining ~7% below seasonal averages suggest limited buffers against further disruptions.
* Rising Russian crude exports, sustained US production and recovering Gulf oil supplies could moderate crude prices, while refinery disruptions and restricted product exports continue to support diesel realisations. Crucially, additional crude availability cannot immediately translate into higher diesel output without sufficient operational refining capacity and export flexibility. Therefore, we expect diesel cracks to remain elevated through FY27, even as global crude availability improves.
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131