Power Sector Update : Robust Demand Visibility; Mixed Margin Trends Across Coverage Choice Institutional Equities
Industry Outlook:
The power T&D outlook remains favourable, with INR 9.15 Tn of grid investment planned by FY32 to expand transmission and evacuate rising renewable power. Healthy order visibility supports demand for 400/765 kV transformers, reactors and bushings. In wires and cables, grid capex, renewables, data centres and infrastructure remain key growth drivers. However, the 11% correction in copper price over the last month and lower aluminium price have triggered 5–6% product price cut, weighing on realisation. Dealer destocking and deferred purchase, amid expectation of further cut and a high Q3FY26 volume base, could moderate near-term growth. Lower input cost may cushion margin, although inventory loss remains a key monitorable.
RISHABH:
Q2FY27 revenue grew 8.4% YoY to INR 2,128 Mn, led by Electrical and Electronic Instruments (EEI) growth, but EBITDA margin contracted 175 bps to 15.2%. The management retained FY27 EEI growth guidance of 20–25% and guides for margin recovery to 20–22%. Lowermargin product mix, delayed commodity pass-through, US tariff and Lumel Alucast loss remain key risks.
RRKABEL:
Q2FY27 revenue grew 51.8% YoY to INR 32,840 Mn, with EBITDA margin expanding to 8.6%. The management revised FY27 Wires and Cables (W&C) volume growth guidance, from 16–18% to 14–15%, reiterating segment EBITDA margin targets of 9.5% for FY27 and 10.5% for FY28. A new entrant with an established dealer network and pan-India presence is intensifying competition and pricing pressure.
YASHHV:
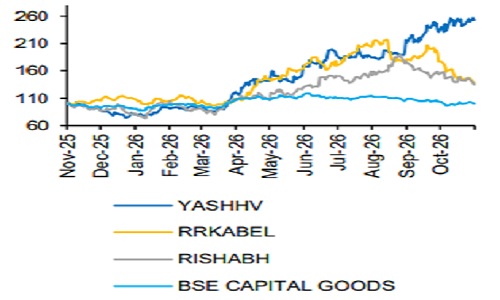
H1FY27 revenue grew 95.3% YoY to INR 1,945 Mn, with EBITDA margin expanding to 27.5%. Order book nearly doubled to INR 7,600 Mn, providing 15–18 months of visibility. Localised cores for up to 245 kV bushings are available from Q4FY27.
We maintain a positive view on the sector and a ‘BUY’ rating on all the three stocks. YASHHV is our top investment idea (TP raised, from INR 1200 to INR 1500; 18.3% upside). Key monitorables include execution, copper price, competition and working capital.
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131