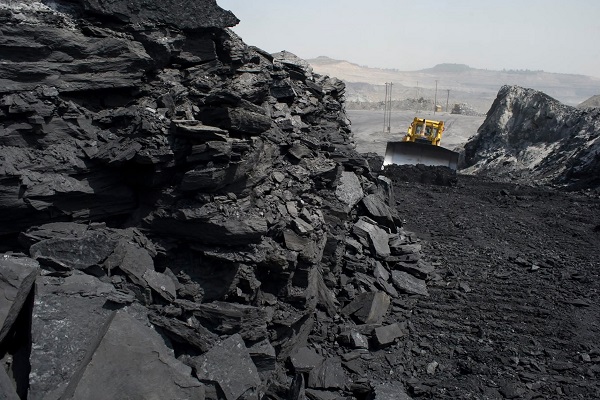
Add Coal India Ltd for the Target Rs 475 by Emkay Global Financial Services Ltd

COAL reported a sharp 2QFY27 EBITDA (ex-OBR) miss, with EBITDA of Rs74bn falling 29%/24% short of our/consensus estimates, driven by weaker eauction realizations and a 12% qoq increase in cost/t amid higher explosives costs. PAT fell 26% qoq to Rs65.5bn, missing estimates by 23-25%. Blended realizations rose 1.4% yoy, with FSA prices up 4.2% yoy to Rs2,192/t, partly offset by lower e-auction premiums averaging 40.6%. Production declined 10.8% qoq to 151.3mt, while offtake stood at 186mt, down 5.8% qoq but up 12.2% yoy. We cut FY27E earnings by 8% but retain FY28-29E volumes, factoring in 4-5% offtake growth supported by robust power demand and potential tightening in Indonesian coal supply. We retain ADD and TP of Rs475.
Sharp EBITDA miss; cost pressures weigh on earnings
COAL reported a significant miss on EBITDA (ex-OBR) performance during 2Q, with EBITDA at Rs73.9bn missing our and consensus estimates by 29% and 24%, respectively. This was mainly driven by lower-than-expected e-auction realizations and a 12% qoq increase in cost/t, partly reflecting higher explosives costs amid Middle Eastrelated disruptions. Reported EBITDA stood at Rs114.5bn, down 17% qoq and below our estimate of Rs138.3bn, while EBITDA/t stood at Rs614 vs Rs725 in 1QFY27. PAT at Rs65.5bn fell short of our/consensus estimates by ~23%/25%, respectively, and declined 26% qoq and 15% yoy. Revenue came in at Rs442bn, down 5% sequentially owing to lower offtake and e-auction realizations, partly offset by a qoq increase in FSA prices. EPS stood at Rs10.6, below both our and consensus estimates. COAL also declared a second interim dividend of Rs10.25/sh, broadly in line with expectations.
Weak production; resilient dispatches
COAL’s blended realizations improved ~1.4% yoy in 2QFY27, although these remained below expectations. FSA realizations rose 4.2% yoy to Rs2,192/t, while e-auction realizations remained broadly flat at Rs3,082/t, with the average premium moderating to 40.6% from 47% in 1QFY27, despite a sharp recovery to 59% in Aug-26 and 94% in Sep-26. Operationally, production declined 10.8% qoq to 151.3mt, albeit up 3.8% yoy, reflecting weaker sequential performance at SECL and WCL. Offtake stood at 186mt, down 5.8% qoq but up 12.2% yoy, supported by higher dispatches from SECL and NCL.
Earnings cut on weak 2Q; maintain ADD
We expect a negative stock reaction following the weak 2QFY27 performance and cut our FY27E earnings by 8%. However, we retain our FY28-29E production and offtake estimates, factoring in 4-5% offtake volume growth, supported by robust power demand and an expected ~7% increase in power consumption. We expect e-auction premiums to stabilize at ~45% over the medium term, with e-auction volumes contributing 13-14% to total offtake. A potential reduction in Indonesia’s coal production target to 700mt in CY26 (vs 790mt in CY25) could provide further support. We retain ADD and TP of Rs475.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH00000035
.jpg)