Buy Premier Energies Ltd For Target Rs.994 By Geojit Financial Services Ltd
Volume Growth Outpaces Margin Pressure
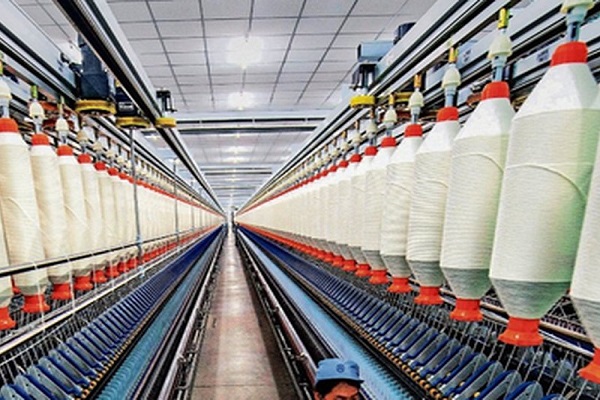
Premier Energies is India’s largest integrated solar cell and module manufacturer, with 10.6GW of cell and 11.1GW of module capacity, and is expanding into transformers, BESS, ingot-wafers and aluminium frames
* Premier’s Q2FY27 revenue from operations rose 43% YoY to Rs.2,632 cr, driven by higher cell and module volumes, with module production at 1,199MW and cell plants operating at record utilisation levels.
* Operating EBITDA grew 31% YoY to Rs.736 cr, but margins contracted by 258 bps to 28%, as commodity inflation in the wake of the Middle East conflict raised raw material costs and squeezed spreads.
* PBT rose 29% YoY to Rs.601 cr, as a 71% fall in other income and higher finance costs offset lower depreciation. PAT grew 31% YoY to Rs.462 cr, aided by a lower tax rate, with margins easing 99 bps to 17%.
* For H1FY27, revenue grew 39% YoY to Rs.5,094cr and EBITDA rose 31% to Rs.1,450 cr, though margins compressed by 186 bps while PAT increased 41% YoY to Rs.934 cr.
* The solar cells and modules segment posted revenue of Rs.2,510 cr at a 28.7% operating EBITDA margin, while transformer subsidiary Transcon reported revenue of ?122 cr at a 13.3% margin
Outlook & Valuation
Premier Energies is set for a stronger H2 as its newly commissioned 7GW TOPCon cell line ramps up, backed by an order book of ~Rs.16,500 cr, of which ~70% is tied to higher-margin DCR demand. Stable DCR pricing and a moderating capex with FY27 guided at ~Rs.2,400 cr and funded internally, add further comfort. We expect working capital to normalise by March 2027 as the new plants stabilise, and BESS and the transformer business should diversify earnings from FY28 onwards. While we cut the multiple on core business as we factor margin pressures due to overcapacity in the industry, we estimate revenue and PAT to grow at a CAGR of 46% and 21% over FY26–28E. We value the stock on a SOTP basis and retain our BUY rating with a revised target price of Rs. 994.
Key Concall Highlights
* The new 7GW TOPCon cell line at Naidupeta has been commissioned and awaits ALMM inspection in November. Management expects 25–30% utilisation in December, rising to ~70% by March 2027, which should drive a step-up in H2.
* New orders of Rs.4,001cr took the order book to ~Rs.16,500cr, with cells and modules at ~48% each and ~68–70% tied to DCR demand. Orders were won at current prices, and management aims to sustain margins.
* DCR module prices remain stable at an average of ~Rs.21.5–22/W, while non-DCR prices have fallen sharply from Rs.14–15/W to ~Rs.12.5/W. Rising aluminium, copper and polymer costs also weighed on module profitability.
* Inventory rose on stocking for new plants and supply delays, and should normalise by March 2027. FY27 capex is guided at ~Rs.2,400cr, funded internally with no QIP planned, while BESS remains on track for Q2FY28.
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH200000345