Commodity Weekly Report November 22, 2026 by Choice Broking
Gold
COMEX Gold prices plunged nearly 9% during the week, falling towards $3,540/oz, their lowest level since September 2025, marking the steepest weekly decline in eight months. The selloff was driven by a hawkish Fed outlook, a stronger US dollar and persistent inflation concerns, with markets pricing in a 99% probability of a 25-bps rate hike in December. Hawkish comments from Fed officials further reinforced tightening expectations, while speculative net-long positions declined by 10,136 contracts to 104,270, indicating weakening investor sentiment. However, lower domestic gold prices revived Indian wedding jewellery demand, although buyers remained cautious. Meanwhile, diplomatic signals from Iran regarding negotiations with the US and the Strait of Hormuz provided some geopolitical uncertainty, keeping market attention divided between monetary tightening and geopolitical developments.
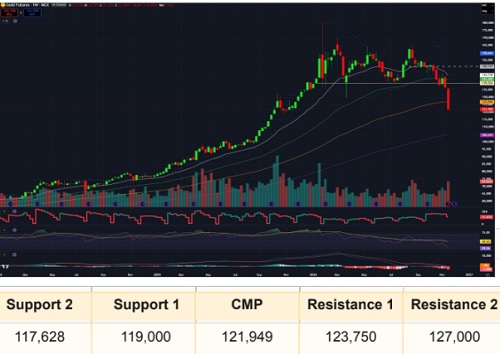
Gold price has continued its downside momentum for another month where price has plunged by more than -11% so far in November. Gold price has managed to settle on a negative note at 121,949 in past week, posted weekly loss of -10.82%. In the past week, price has resumed session with gapped down in every other day and we have observed a formation of Death crossover on Daily timeframe, indicating mid-to-long term bearish bias. However, traders should considered this decline on a caution note as OI levels has been declined to 11,470 lots in current expiry, indicating Short covering towards expiry. The momentum indicator, RSI levels has been dropped below 30 on daily and weekly timeframe. Also, we can observe a bearish crossover in monthly MACD above zero-line along with negative histograms. Crucial support would be at 117,628.
The overall trend in price is expected to be Moderately bearish in the coming week, and traders should keep an eye on key US economic data such as Core PCE price index, Prelim GDP, Personal spending, Consumer confidence & Unemployment claims which are scheduled to be in next week.
Silver
COMEX Silver plunged more than 14% this week logging its steepest weekly decline in eight months as a firmer US dollar, hawkish Federal Reserve signals, and a broad selloff in AI-linked equities weighed heavily on the metal. Following warnings over upside inflation risks from Philadelphia Fed President Anna Paulson and October FOMC minutes, markets are pricing in a 96% probability of a 25-basis-point rate hike in December. Meanwhile, global equity market turmoil triggered liquidity-driven liquidations across precious metals, compounding industrial demand concerns. On the fundamental front, silver is projected to record its sixth consecutive annual supply deficit in 2026 despite a 5% demand dip, though softer solar demand could gradually steer the market toward surplus.
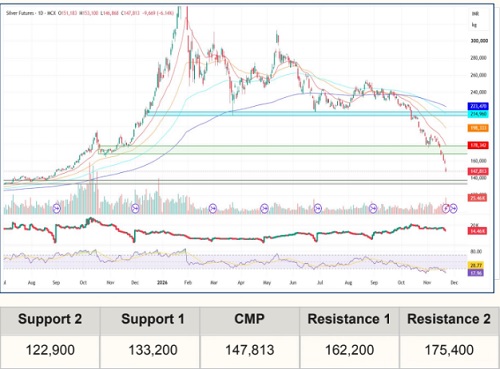
MCX Silver prices continued to witness sharp selling pressure, touching a fresh 15-month low and closing the week at ?1,47,813. Prices are trading significantly below all key moving averages, with the 20-50-100-200 DEMA placed at 178342, 198333, 214960 and 223470, respectively. Prices are also trading below key weekly EMAs, indicating sustained weakness across short- and medium-term timeframes. The RSI has slipped to 17.96, reflecting deeply oversold conditions and highlighting the possibility of intermittent technical recovery. Open interest declined at 14,460 lots alongside falling prices, suggesting long unwinding in the market. Meanwhile, the Gold-Silver ratio has climbed to 85.7:1, its highest level in nearly 13 months.
Overall, the outlook for MCX Silver remains bearish. Traders may look for sell-on-rise opportunities in the short term, while exercising caution near lower support levels due to extremely oversold momentum.
Crude Oil
WTI Crude oil settled at $83 per barrel, marking a third consecutive weekly decline as abundant supply projections overshadowed Middle East geopolitical risks. The IEA projected a supply surplus of around 2 million bpd this quarter, while recovering Middle Eastern output and record oil flows through the Strait of Hormuz eased supply concerns. Goldman Sachs also warned of potential oversupply next year. The US, China, and Russia agreed at a trilateral meeting to boost the production and supply of refined petroleum products. Meanwhile, mixed geopolitical signals kept traders cautious. While immediate escalation fears eased as President Trump delayed strike decisions amid Pentagon warnings of overstretched forces. Despite Iranian Foreign Minister Araghchi maintaining Strait closure conditions, ongoing Qatari-mediated talks suggest diplomacy remains viable, keeping downward pressure on crude.
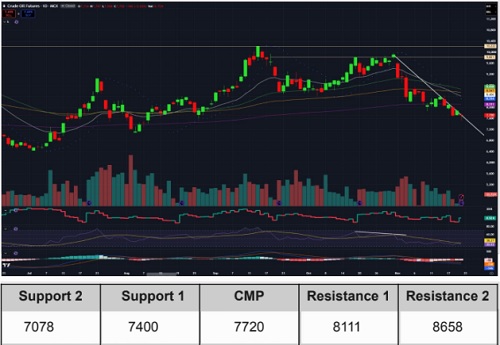
Crude oil price has posted weekly loss for another week where price has dropped by -7.79% in past week and closed at 7720. On past Friday, price has managed to rebound from the support low of 7508. On continues chart, price has continued to trade below bearish trend line, sustaining below its all key moving averages i.e. 50, 100 and 200-DEMA levels placed at 8658, 8547 and 8111 respectively. Major support would be at 7078 and breakout below this mark will boost downside momentum in Crude oil price in upcoming sessions. Daily SAR is placed at 8314. RSI levels has trailed between 35 - 45 range on Daily and Weekly chart. Also, we can observe a bearish crossover in Weekly MACD above zero-line along with negative histograms, collectively suggests bearish bias.
We are expecting Sideways-to-Bearish trend in Crude oil in upcoming sessions and traders should look forward for Sell-on-rise opportunity.
Natural gas
US Natural gas prices gained around 4.5% during the week, extending gains for a fourth consecutive week, supported by forecasts of colder weather and rising heating demand towards the end of November. The EIA reported a below-expected storage injection of 20 Bcf, although inventories remained 2.1% above seasonal norms, limiting further upside. Higher LNG shipments and approval for Cheniere Energy’s Sabine Pass expansion improved the longer-term export outlook. In Europe, gas prices remained supported by geopolitical tensions, Norwegian supply disruptions and colder weather expectations. Concerns over winter supply intensified following SSE’s planned closure of the Atwick storage facility, while European gas inventories stood at 70.15%, significantly below last year’s 81.9%, reinforcing supply tightness concerns
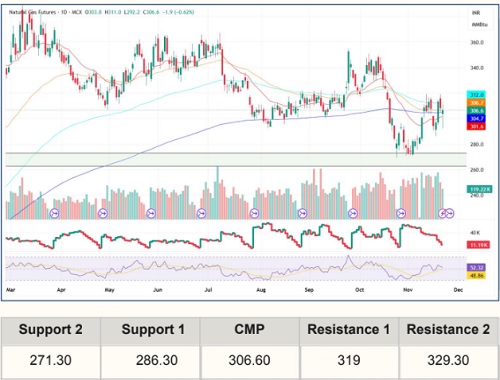
MCX Natural Gas prices witnessed a sideways-to-bullish recovery during the week, closing at 306.60. Prices are trading above the 20 and 200 DEMA placed at 304.70 and 301.60, respectively, while facing resistance near the 50 and 100 DEMA at 312 and 306.60. This indicates improving momentum, although the prices are yet to establish a decisive breakout above the immediate resistance zone. The RSI is hovering around 52.32, suggesting a gradual improvement in buying momentum.Open interest declined to around 23,000 lots, indicating reduced market participation during the recovery.
Overall, the outlook for MCX Natural Gas remains sideways to bullish, with the possibility of further upside if prices sustain above the immediate resistance zone. Traders should wait for a decisive breakout for confirmation of bullish momentum before considering fresh long positions
Copper
LME Copper prices plunged more than 12% this week as a broader financial market rout—driven by unwinding AI investments, US interest rate jitters, and a firmer dollar—triggered heavy fund selling across both sides of the Atlantic. Macro headwinds and Chinese industrial demand concerns overshadowed acute physical tightness. Although SHFE inventories edged up slightly, they still cover less than a day’s domestic consumption, pushing Chinese domestic and Yangshan import premiums higher. Tight raw material supply is also slowing China’s refined output to its weakest annual growth in decades, following a 12.5% year-on-year drop in nine-month refined imports. Meanwhile, the CME copper premium has contracted sharply into a spot discount to LME, easing earlier US tariff-driven competition for physical units. On the data front, In Asia, China will report industrial profits for the year to October
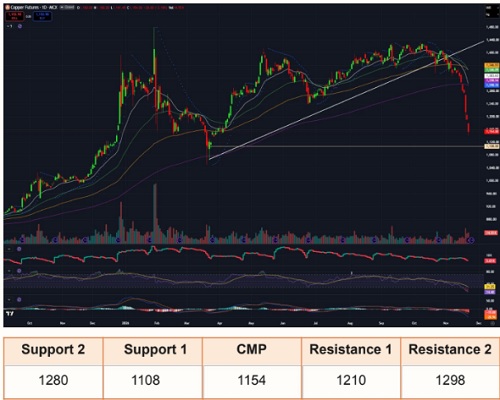
Copper price has continued to posted a weekly loss for 6th consecutive week where price has declined by more than -10% in past week after almost 85 weeks, managed to close at 1154. After a breakout below bullish trend line, price has dropped marginally and started trading below its key moving averages i.e. 50 and 200-DEMA levels placed at 1346 - 1299 respectively. Daily SAR is also placed at 1298.35. Major support would be at 1108 and breakout below this mark will boost downward momentum in Copper price in upcoming sessions .
We are expecting Sideways-to-Bearish trend in Copper in next week and traders should look forward for Sell-on-rise opportunity.
Zinc
LME Zinc prices fell more than 5% over the week, dragged down by cautious market sentiment and expectations of improving refined metal supply. Following maintenance completions, smelter restarts across Henan, Xinjiang, and Anhui are set to boost availability. While China’s refined zinc output dropped 3.5% month-on-month and 12% year-on-year in October, Consequently, LME three-month prices declined faster than cash settlement prices, reflecting softer forward sentiment as warehouse stocks rose 2.1% week-on-week to 145,675 tonnes after peaking at 148,375 tonnes mid-week. Market participants will monitor Chinese smelter output, concentrate treatment charges and LME warehouse movements for signs of whether improved refined supply translates into higher deliverable metal availability.
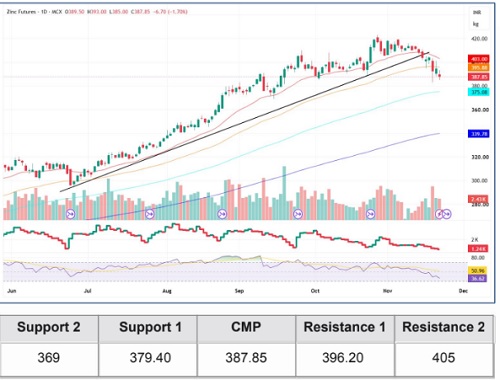
MCX Zinc prices witnessed a sharp correction, declining to a low of 383 and closing at 387.85. The prices have slipped below the 20-50 DEMA, placed at 403 and 395.88, respectively, however, the contract continues to trade above its 100-200 DEMA, positioned at 375.08 and 339.78, respectively. From an indicator perspective, RSI stands at 36.62, below its average of 50.96, reflecting weakening momentum and increasing bearish pressure. Open interest declined at 1240 lots, this suggests that the recent correction may largely be driven by profit booking and liquidation of existing long positions.
Overall, Zinc is expected to remain moderately bearish in the near term, with traders advised to remain cautious around key support levels. while a decisive breakdown could intensify selling pressure.
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131