The Alternate Opinion : Industrial weakness contrasts with Tech crowdings by Elara Capital
Global equity flows remained strong for a second week, largely supported by a 13-week high inflow into China from domestic investors. Domestic investors poured $17bn into China equity funds this week amid the sharp correction. A similar buying surge during the Jun’26 correction preceded a 15% rally in China. However, foreign investors are yet to make incremental allocations to China. Importantly, flows into S.Korea and Taiwan also accelerated during the correction. S.Korea-dedicated funds saw their largest inflow in 15 weeks at $5.8bn, while Taiwan recorded a record $6.9bn inflow. The Kospi has reached its Jul’26 panic lows, attracting strong buying interest. Taiwan’s correction has also brought the index to its 100-day moving average, a level that has supported every correction since Jun’25
Inflows into US funds continued at a slower pace of $7.3bn, versus $40bn in the previous week. GEM inflows rose to a 12-week high of $2.8bn as the EM index correction approached its Jul’26 lows. Global Semiconductor funds also saw their largest inflow in seven weeks at $3.9bn, as the Philadelphia Semiconductor Index touched its 200-day moving average for the first time since May’25. Fund flows are therefore regaining momentum across regions and sectors where key technical support levels have been reached.
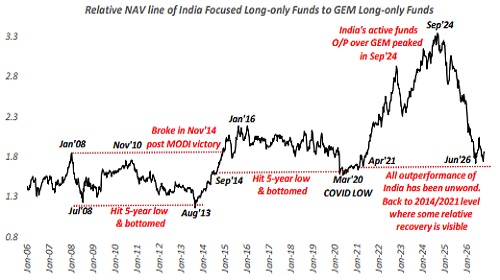
Outflows from India-dedicated funds slowed to a six-week low of $175mn, following average weekly redemptions of $440mn over the previous five weeks. Long-only funds continue to account for the bulk of these outflows. However, India-dedicated long-only funds have stopped underperforming GEM long-only funds over the past four months. Their relative NAV line has reached levels last seen in Sep’14 and Apr’21. This could be an important factor in reducing foreign investors’ incentive to reallocate away from India towards other EMs.
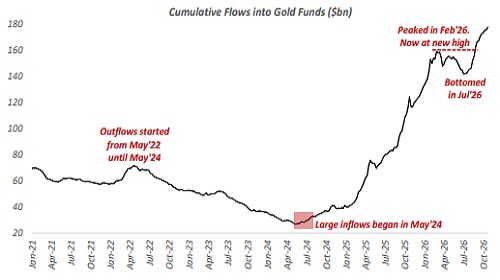
Inflows into Gold funds continued at a slower pace of $2bn this week, while Silver inflows rose to an eight-week high of $335mn. The long-term flow trend remains stronger for Gold than for Silver. Global Industrial funds saw further outflows of $905mn, although these have moderated from the previous week’s record redemption of $1.6bn. The sector’s long-term flow momentum is weakening for the first time since the AI trade began in May’25. In contrast, Global Technology funds—which provide more direct exposure to US technology stocks—attracted another $19bn, their largest inflow in four months. Crowding into US Technology stocks continues unabated.
Above views are of the author and not of the website kindly read disclaimer