Quote on FPI Flows in Indian Markets for the week of 9-13 November 2026 by Dheeraj Gaur, Chief Investment Strategy Officer at Choice Wealth
Below the Quote on FPI Flows in Indian Markets: for the week of 9-13 November 2026 by Dheeraj Gaur, Chief Investment Strategy Officer, Choice Wealth
Foreigners kept buying for a second week, quietly and in size, while the Nifty paused for breath. The bill for all that good news arrived on Tuesday in the form of US inflation.
Equity Flows: Another big week, with less fireworks
Diwali shortened the week: Muhurat trading on Sunday, a holiday on Tuesday, and four regular sessions. FPIs were net buyers every single day. On provisional NSE numbers they bought Rs7,212 crore on Monday, Rs12,563 crore on Wednesday, Rs7,831 crore on Thursday and Rs5,737 crore on Friday. Net, about Rs33,340 crore of buying – smaller than last week’s Rs45,960 crore, but still one of the biggest weeks in years. FPIs sat out the Sunday Muhurat session. DIIs, who spent weeks absorbing foreign selling, sold about Rs24,190 crore over the week.
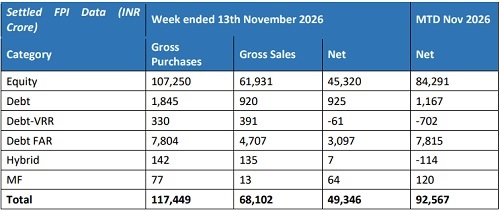
The settled numbers are even bigger. The week’s four custodian reports show FPIs as net buyers of about Rs45,320 crore in equities – roughly Rs14,768 crore on Monday’s report, Rs6,959 crore on Wednesday’s, Rs14,694 crore on Thursday’s and Rs8,899 crore on Friday’s. Only about Rs60 crore came from the primary market, so this was almost entirely secondary-market buying.
In first half of November, FPIs flows at +Rs84,291 crore on a settled basis – roughly 2.4 times October’s Rs34,843 crore outflow are easily the highest since December 2020. Calendar-2026 outflows have shrunk to roughly Rs2.1 lakh crore from about Rs3 lakh crore a few weeks ago.
For the detail-minded:
So, what did the market do with it?
Not much, which is probably healthy after +8.6% the week before. The Nifty rose 0.5% to 25,144 and the Sensex 0.7% to 81,592, a third straight weekly gain, though Friday was a 0.6% fall as inflation and oil came back into view. The big change was breadth: the Nifty Smallcap index gained 3.6% and Midcap 2.1%, after lagging badly the week before, and PSU banks led the sectors. In other words, the foreign money that went into large-caps last week started to trickle down the market-cap ladder this week.
In short: after buying the building, FPIs spent the week buying the furniture.
Debt Flows: FAR keeps coming back
Debt was positive again. Across the week’s reports, FPIs bought about Rs3,097 crore through FAR and Rs925 crore through the general limit, with a small Rs61 crore of VRR selling. Net, about Rs3,960 crore of debt inflows. FAR was choppy day to day – Rs3,041 crore on Monday’s report, a Rs1,174 crore outflow on Wednesday’s, then Rs1,023 crore and Rs207 crore – but it has now added about Rs7,815 crore in November, after losing Rs6,986 crore in October. Debt is up about Rs8,280 crore for the month in total.
The rupee was the soft spot. After touching a six-month high near Rs93.91 the week before, it weakened marginally to close at about Rs94.24 on Friday, as US yields rose firming up the dollar. That is a modest slip, but it is exactly the thing FAR investors watch.
Is the story still intact?
Mostly, with two new wrinkles. US inflation came in hot: October CPI rose 0.4% on the month against 0.3% expected, and core CPI rose 0.3% for a third straight month. The 10-year Treasury yield jumped back towards 5%, and a December Fed hike is now close to fully priced (roughly 90% or more, with a 50 bp move getting a 10–15% chance after Governor Waller’s comments).
India’s own inflation also surprised: October CPI came in at 6.09%, above the 5.93% expected and just above the RBI’s 6% upper band, its 12th straight monthly rise. That keeps the door open to another RBI hike in December or February. Oil is a mixed picture: Brent traded between about $90.6 and $96, ending near $96 (roughly 2.5% lower on the week), but it jumped on Friday after reports of attacks on Saudi energy infrastructure and Hormuz disruptions, and on comments from President Trump that he would not hesitate to resume strikes on Iran.
The silver lining, if you want one: FPIs kept buying through a hot US CPI print, a rising Treasury yield and a weaker rupee. That is a sturdier kind of buying than the first week’s relief rally. The catch: the best of the oil relief seems to be behind us and these two central banks are leaning hawkish.
As I wrote in my commentary for the last week of September 2026 – FPI flows were largely linked to global asset-allocation and risk management than a wholesale loss of confidence in India’s underlying domestic growth story – I continue to believe that India will be one of the biggest beneficiaries of the unwinding of “AI Trade”, should the domestic macros remain intact.
What to watch next week?
A full five-session week, with no holidays. What will matter for FPI flows:
* The Fed. FOMC minutes are due on Wednesday, 18 November and with a December hike largely priced, the debate is 25 bp versus 50 bp. Fed speakers will matter.
* Brent, Iran and the Gulf. Oil has swung between $90 and $98 in two weeks; a break in either direction will move the rupee and FAR flows.
* The rupee and RBI. Whether USD/INR holds around Rs94 and whether the 6.09% CPI print starts to move expectations for a December RBI hike.
* Breadth and earnings. Mid- and small-caps finally joined the rally; the tail end of Q2 results may just make the rally last a bit longer.
* Nifty levels. The index closed at 25,144; if it holds above 25,000, it may keep the rally intact.
* Continued unwinding of “AI Trade”. That’s the tail wind blowing towards us
Bottom Line: Foreigners bought again – about Rs45,320 crore on settled data, almost all of it in the secondary market. November has already reached +Rs84,291 crore on a settled basis and debt (mainly FAR) was encouraging too. Hot US and Indian inflation, a weaker rupee and an unsettled oil price are the tests ahead. So far, FPIs have shrugged them off
The views are personal. Data points are referenced from publicly available information, internal sources and other third-party sources believed to be reliable. While every care has been taken to ensure veracity of data, however, the writer cannot guarantee the accuracy of such information, assure its completeness, or warrant that such information will not be changed. The information in this report may include inaccuracies or typographical errors. Investors are advised to consult their investment managers/advisors and read all documents carefully before investing.
Above views are of the author and not of the website kindly read disclaimer

More News
Quote on Pre Market Comment November 13th 2026 by Deepesh Sarawagi Technical Research Analys...