Equity Outlook : Equity Outlook for November 2026 by George Thomas, Fund Manager-Equity, Quantum AMC
Indian equities were range bound in October as elevated crude prices and a mixed earnings season weighed on sentiment. As expected, input-cost inflation weighed on margins across several sectors. Foreign investors remained net sellers amid elevated global yields. With domestic inflation still above the RBI's target, further rate hikes are likely in the near term. A prolonged period of high crude and rising rates would weigh on both earnings and valuations.
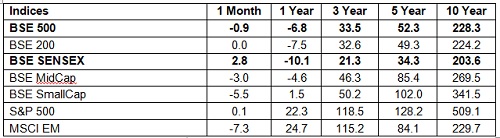
Source: Bloomberg, Data as of 31st October 2026.
Past performance may or may not be sustained in the future.
Q2FY27 Earnings: A Mixed Bag
Higher input costs weighed on Q2FY27 earnings. With crude and bond yields high and the West
Asia crisis unresolved, cost pressures are likely to persist in the near term.
IT services
* Revenue growth was muted, but steady deal wins and stable margins suggest the peak of the repricing on existing contracts is behind us.
Banks & financials
* Loan demand held up, but margins narrowed on the higher cost of recently raised FCNR deposits. As the recent rate hike feeds through to loan yields, margins should improve from here.
Autos
* Volumes were strong in two-wheelers, passenger vehicles and CVs. Last year’s GST rate cuts are still lifting demand, along with a healthy replacement cycle. Growth is likely to moderate in H2 as the comparison base now includes the post-GST-cut months.
Industrials, capital goods & engineering
* Industrials and capital goods continued to post strong growth, driven by government capex and infrastructure execution. Grid upgrades and data-centre demand should keep momentum strong in the near term, though higher input costs remain a risk to margins.
Metals, materials & cement
* Higher energy costs and geopolitical risk are pressuring margins, and investors have become more cautious on the group. Muted global growth and rising interest rates are likely to weigh on metal prices over the medium term. Cement volumes are holding up, but elevated fuel costs will keep profitability under pressure in the near term.
Real estate
* Sales held up on urban demand, and project execution continues to gain pace. Higher interest rates and inflation could weigh on affordability in the near term.
Consumer & retail
Premium categories and durables did well, while mass-market and non-durables were soft. Earnings followed suit, with premium discretionary names ahead of mass-market consumer companies.
Near-Term Drivers We Are Watching
* West Asia - Crude remains the key swing factor for India’s growth and inflation, and a durable resolution of the crisis is critical to the growth outlook.
* Earnings and input costs - Earnings growth is likely to moderate as companies would pass on crisis-driven cost increases with a lag, particularly in cement, autos, capital goods and chemicals. The market is likely to look through this near-term headwind , since a durable resolution in West Asia would ease input prices over the medium term.
* Rural demand - With the monsoon season over and being lower than long term average, the focus shifts to kharif output and rabi sowing, which will shape rural incomes and food inflation over the coming months.
* FPI trajectory - Foreign flows hinge on India’s relative earnings growth, currency stability and US yields. If growth slows in the AI-linked stocks that have drawn global money, India’s earnings growth would look attractive in comparison and could bring flows back.
Global yields and monetary policy - Higher US policy rates and elevated long-term bond yields could keep global liquidity conditions tight. A higher cost of capital would weigh on valuations across global markets, including India, with pronouncedimpact in segments trading at a premium to their historical averages
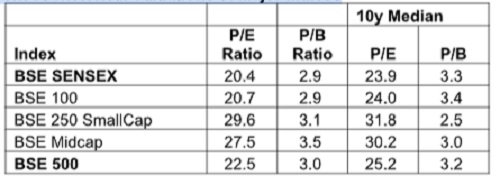
Table 2: Current vs Historical Valuations of Major Indices
What Can an Investor Do?
Although the near-term earnings trend is tied to global developments, valuations have turned
attractive in several pockets; large-caps are trading below their 10-year median multiples.
Volatility is likely to persist while the geopolitical situation evolves but short-term uncertainties
do little to change the intrinsic value of businesses. Investors may consider fresh equity
allocations in the near term to benefit from reasonable valuations.
Above views are of the author and not of the website kindly read disclaimer