DSP Mutual Fund's Tathya : Monthly Macroeconomic and Market insight Report
In this material DSP Asset Managers Pvt. Ltd. (the AMC) has used information that is publicly available, including information developed in-house. Information gathered and used in this material is believed to be from reliable sources. The AMC however does not warrant the accuracy, reasonableness and / or completeness of any information. The above data/ statistics are given only for illustration purpose. The recipient(s) before acting on any information herein should make his/ their own investigation and seek appropriate professional advice. This is a generic update; it shall not constitute any offer to sell or solicitation of an offer to buy units of any of the Schemes of the DSP Mutual Fund. The data/ statistics are given to explain general market trends in the securities market and should not be construed as any research report/ recommendation. We have included statements/ opinions/ recommendations in this document which contain words or phrases such as “will”, “expect”, “should”, “believe” and similar expressions or variations of such expressions that are “forward looking statements”. Actual results may differ materially from those suggested by the forward looking statements due to risks or uncertainties associated with our expectations with respect to, but not limited to, exposure to market risks, general economic and political conditions in India and other countries globally, which have an impact on our services and/ or investments, the monetary and interest policies of India, inflation, deflation, unanticipated turbulence in interest rates, foreign exchange rates, equity prices or other rates or prices etc.
Key highlights:
* The growth in demand has sustained. On an absolute basis, the consumption bit has improved.
There is no segment that looks particularly worrying, most are holding up reasonably well.
* Manufacturing has picked up decently. WPI faces pressure, but that bakes in the elevated levels of oil price which did materialize into higher fuel prices. This adversity remains till the uncertainty and volatility in oil prices remains.
* The indicators below have shown little to meaningful pickup compared to the past year (compare absolute 12M avg numbers with the past year).
Notably, housing loans, a segment that had held up well, have also slipped to low double-digit growth.
* Expenditure and revenue profiles, have not picked meaningfully as compared to the past year (compare absolute 12M avg numbers with the past year).
* We are comfortable, as far as liquidity is concerned. However, we should not confuse this with comfortable money supply.
India has had a reasonable uptick in credit growth, it can do with more.
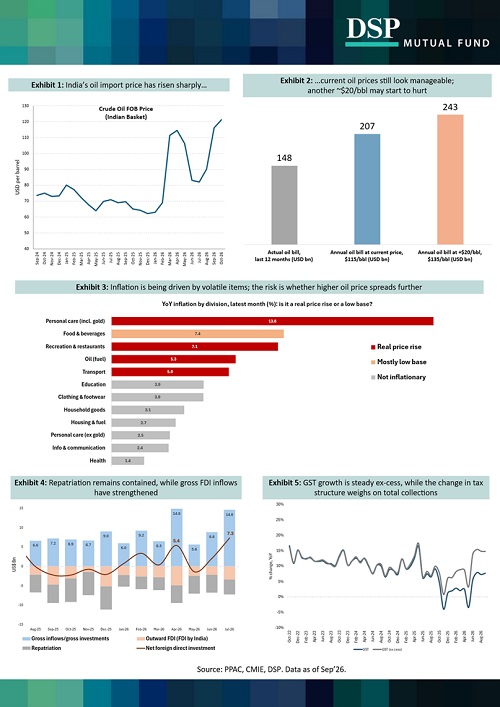
* Oil Balance, without doubt, has been the story of the season. But Non-oil balance/imports have decently held ground. The adverse impact of higher oil prices have not materially creeped into the broader import basket, till now.
With crude oil price inching higher, the anxieties around BOP may not be as contained. (See Exhibit 1&2)
* When valuations for India equities were sky high, we highlighted how fragile the system had become to foreign investment outflows. Today we are at the other end.
It is at such valuations that the environment becomes particularly conducive to flows. But MF equity flows, which remained rather strong through most of the bull market, have begun to look patchy now.
Above views are of the author and not of the website kindly read disclaimer