Consumer Sector Update : Demand remains muted, 2H Sept key to watch out for by PL Capital
We remain cautious on the near-term paints demand outlook, based on our latest channel checks. Secondary sales remain subdued across regions and brands, including Asian Paints and Birla Opus, while dealers continue to focus on inventory correction following elevated stocking over the past two quarters. The second half of September remains a key monitorable as festive-led stocking is expected to commence and weaker monsoon conditions, aided by El Niño are likely to support a pickup in painting activity. The pace and sustainability of the recovery in late Sept will be critical in assessing demand trends in coming quarters.
We believe the combination of channel destocking, muted premium/luxury demand and elevated competitive intensity might keep near-term volume growth under pressure across brands.
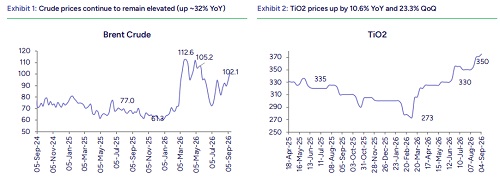
We estimate sales CAGR of 9.9%/8.6% for Asian Paints/Kansai Nerolac over FY26– FY28, with EPS CAGR of 11.9%/10.9%, respectively. At 41.1x/18.1x FY28E EPS, valuations appear reasonable, particularly for Kansai Nerolac. However, we see limited near-term triggers for both companies amid 1) weak demand visibility 2) sustained competitive intensity and 3) rising crude and RM prices. Further, the recent sharp uptick in crude prices and inflationary pressures could weigh on consumer spending and limit near-term demand momentum. We therefore remain cautious on paints sector with limited near-term demand visibility despite reasonable valuations. Although we expect QoQ moderation in margins, lower margins in the base quarter will enable double digit EBIDTA and PAT growth.
Paints Channel check: Sept end holds key to Secondary sales remain weak
• Our channel checks indicate moderation in paints demand, with secondary sales declining in single digits YoY across regions and brands through July & August.
• Dealers highlighted that monthly sales targets were missed over the past two months, indicating that the weakness is not merely a one-off disruption but reflects broader moderation in offtake.
• However, the last 15 days of September remain critical, with dealers expecting demand to pick up on the back of the festive season and improving construction activity as monsoon tapers off.
• A recovery in 2H September offtake would be important to assess whether the recent demand softness is temporary or indicative of a more sustained moderation.
• The key driver of the current moderation appears to be trade inventory normalisation post elevated channel stocking over the past two quarters. Strong primary sales during the preceding period were partly supported by inventory build-up across the channel. As dealer inventory levels were relatively elevated, replenishment had moderated, leading to softer secondary sales and consequently lower primary offtake.
• Consumer spending remains cautious, with discretionary spending on paints being deferred amid elevated inflation in key daily use household essentials. This is further weighing on near-term demand and limiting the pace of channel replenishment.
Asian Paints/Birla opus also witnessing secondary demand moderation
• Asian Paints channel checks indicate weaker secondary sales for the market leader with latest channel feedback suggests that underlying secondary demand has weakened entering 2QFY27, making the 8–10% volume-growth guidance for FY27 increasingly dependent on a recovery in the coming months, particularly around the festive period.
• The slowdown appears to be broad-based across brands, with channel checks indicating secondary sales declining YoY across regions. Even Birla Opus is witnessing muted sales demand with secondary sales down in low single digit on a YoY basis.
• That said, competitive intensity remains at elevated levels, across economy, premium and luxury segments, with Birla Opus & JSW Akzo continue to gain ground.
Price hike observed in some company, more hike possible if crude remain above $100
• Channel checks indicate that select players have implemented a 2–3% price hike in August; however, APNT did not undertake any incremental price increase.
• Dealers expect some price hikes ahead of the festive season, supported by sustained firmness in crude prices above US$100/bbl.
Please refer disclaimer at Report
SEBI Registration number is INH000000933
More News
Cement Sector Update : Q3FY26 Quarterly Results Preview Choice Institutional Equities