Construction materials sector revenue growth forecasted to reach 9.1% by FY27: Brickwork Ratings
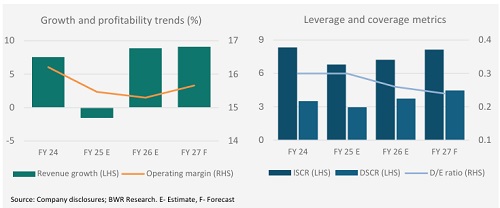
According to Brickwork Ratings (BWR), revenue growth in the construction materials sector is likely to witness a positive turnaround, moving from a contraction of 1.5% in FY25 to a growth of 8.9% in FY26 and 9.1% in FY27. “This turnaround is largely driven by sustained capital expenditure on infrastructure spending by GoI, strong order books, and new urban housing schemes,” says Niraj Rathi, Senior Director, Ratings, Brickwork Ratings.
Profitability fueled by upcycle in residential real estate, Grade-A warehousing
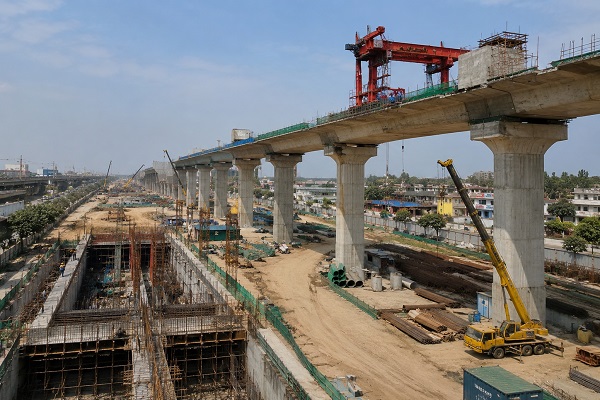
The sector, which includes key materials such as cement, concrete and structural steel, is benefiting from the ongoing infrastructure and urban housing cycle. The PM Awas Yojana (Urban) 2.0, which targets construction of one crore houses for the urban poor under the FY26-FY30 period, is expected to support demand.
Revenue growth and operating margins are also being supported by rising demand for sustainable infrastructure materials and Quality Control Orders (QCOs) on wood-based panels, alongside higher domestic realisation. “The sector is seeing a structural increase in demand from real estate and Grade-A warehousing, supporting demand and pricing for backend building materials such as cement,” adds Rathi.
Financial profile remains strong, supported by low gearing
BWR expects operating margins to improve from 15.5% in FY25 to 15.3% in FY26E and 15.7% in FY27F. The sector's financial health is supported by very low gearing, with the debt-to-equity ratio expected to decline from 0.30 in FY25 to 0.24 in FY27F.
Interest coverage is projected to improve from 6.8 times in FY25 to 7.2 times in FY26E and 8.1 times in FY27F. Debt service coverage is also expected to strengthen, from 3.7 times in FY26E to 4.5 times in FY27F, providing smaller and mid-sized firms with adequate headroom to manage working-capital requirements without significant debt-servicing stress.
Input costs and execution delays remain key risks
Despite healthy demand, potential spikes in raw material and energy prices remain a key risk, particularly for cement and specialised material segments. Slower project execution and delays could also affect revenue recognition and working-capital cycles.
Credit outlook remains stable
“We expect the sector's credit outlook to remain stable, backed by infrastructure and urban housing activity. Specialised products such as plastic pipes and wood panels are seeing demand growth, while manufacturers are largely funding capacity expansion through internal accruals rather than bank loans, keeping debt levels low through FY27F,” concludes Rathi.
Above views are of the author and not of the website kindly read disclaimer