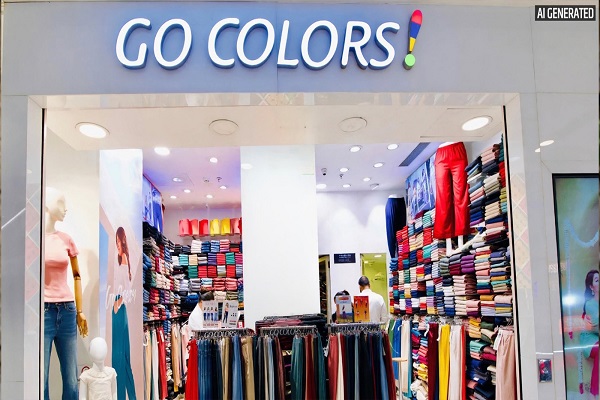
Buy Go Fashion (India) Ltd For Target Rs.300 by Motilal Oswal Financial Services Ltd
Soft quarter on festive timing and costs; recovery levers intact
* Go Fashion reported a weak 2QFY27, with revenue declining 3% YoY (in line) as the festive shift pushed LFS dispatches into Oct’26, while EBO SSSG was broadly flat at -0.2% (vs. +0.2% in 1H).
* Pre-Ind AS EBITDA (ex-one-offs) declined 40% YoY to INR200m in 2Q, with margin contracting 570bp YoY to 9.2%, as RM pressure (~180bp) from fabric inflation and higher brand investments weighed on profitability. H1 EBITDA declined 25% YoY to INR513m, with margins down 380bp to 11.6%.
* Larger stores are delivering 2–3%+ SSSG, while weakness is concentrated in 120–150 smaller stores. Store closures dipped to 23 in 2Q from 66 in 1Q and should moderate to 15–20 in 3Q, reducing the drag from consolidation on 2H growth.
* Early festive trends are encouraging and should support stronger 2H growth, though gross margins could face a further hit in 3Q before price hikes take effect.
* Accordingly, we trim our EBITDA estimates by 5-8% and now model a revenue/Pre-IND AS EBITDA/PAT CAGR of 8%/16%/15% over FY26–29E on a low base.
* At ~13x TTM pre-Ind AS EV/EBITDA, the stock already reflects near-term margin pressure, while a debt-free balance sheet with INR2.5b of cash (~20% of market capitalization) funds the larger-store transition. We reiterate our BUY rating with a TP of INR300, based on 10x FY28 pre-IND AS EV/EBITDA.
Performance: 1HFY26
* Go Fashion’s 1HFY27 revenue declined 1% YoY to INR4.4b, as 2% YoY EBO growth to INR3.2b (SSSG +0.2%) and 20% online growth were offset by an 8% decline in LFS to INR1.0b due to the shift in festive dispatches.
* Gross margin contracted ~95bp YoY to 61.8%, driving a 16% decline in reported EBITDA to INR1.1b (margin down 450bp to 25.8%) and a 42% fall in PAT to INR254m.
* Pre-Ind AS EBITDA (ex-one-offs) fell 25% YoY to INR513m, with margin contracting 380bp YoY to 11.6%, as gross margin pressure and higher other expenses (+23% YoY) weighed on a flat revenue base.
Balance sheet and cash flows
* Working capital stood at 134 days (flat YoY). Inventory fell by 5 days to 94, partly offset by a 4-day rise in payable days to 12. In absolute terms core working capital stood at INR3.2b (down 7% YoY)
* Despite muted profitability, working capital release led to healthy 1HFY27 preInd AS operating cash flow of INR526m (up 2x YoY), translating into ~103% cash conversion from pre-Ind AS EBITDA.
* The company ended the quarter with INR2.1b of cash and investments, maintaining a debt-free balance sheet.
Valuation and view
* The network reset has limited the revenue impact, with 1H revenue declining just 1.5% YoY despite 89 EBO closures. Retail area increased 3% to 0.44m sqft as sales migrated to nearby larger stores. Lower closures should support better growth from FY28.
* Premiumization is supporting realizations, with value-added products contributing 70% of revenue and ASP rising 6% YoY to INR827, driven entirely by product mix. Recent price hikes are yet to flow through, providing an additional realization lever.
* The long-term opportunity remains attractive, with branded women's bottom wear expected to grow at ~17% CAGR to INR242b by FY29. Go Fashion holds ~8% market share, with a scaled presence across major bottom wear categories.
* We trim our EBITDA estimates by 5-8% and now model a revenue/Pre-IND AS EBITDA/PAT CAGR of 8%/16%/15% over FY26–29E on a low base.
* At ~13x TTM pre-Ind AS EV/EBITDA, the stock already reflects near-term margin pressure, while a debt-free balance sheet with INR2.5b of cash (~20% of market capitalization) funds the larger-store transition. We reiterate our BUY rating with a TP of INR300, based on 10x FY28 pre-Ind AS EV/EBITDA.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412




.jpg)