


Buy GE Vernova T&D India Ltd for the Target Rs 5,100 by Motilal Oswal Financial Services Ltd
Execution visibility remains strong
In our recent meeting with GE Vernova T&D (GVTD), management highlighted improved activity in the transmission tendering in domestic markets. The company’s recent L1 win in Barmer HVDC project, along with existing South Olepad HVDC project, can potentially take its order book above INR300b, providing revenue visibility of 4-5 years. GVTD is optimistic about the finalization of more HVDC projects over next one year. Large export orders are taking some time to finalize. The company’s capex plan is aligned to cater to existing and incremental demand. We slightly tweak our margin estimates to bake in the impact of current RM prices and maintain BUY with a TP of INR5,100, based on average of DCF and 58x P/E Dec’28E EPS
Recent HVDC win boosts order book and revenue visibility
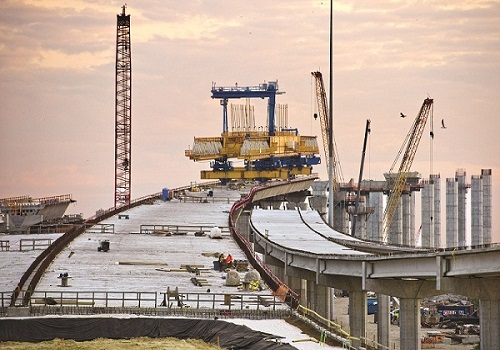
GVTD was recently declared L1 in Barmer-South Kalamb HVDC project from Powergrid. This is GVTD’s second HVDC project after South Olepad HVDC project awarded in FY26. Its scope of work would include establishment of 6GW, ± 800 kV high-voltage direct current (HVDC) LCC terminal station (2x3000 MW) from Barmer II to South Kalamb. The company expects execution from this project to commence from FY28 and meaningfully pickup from FY30. The execution from the previously awarded South Olepad HVDC project will also commence from FY27 and meaningfully pickup from FY29. Thus, we believe that contribution from HVDC projects will start ramping up sharply from FY29 itself for the company. After incorporating this project, the company’s order book would increase to more than INR300b, thereby giving a strong visibility for the next five years of execution. We expect revenue to grow at 26% CAGR over FY26-29.
Few more HVDC projects on the anvil along with base ordering ramp-up
GVTD also expects three more HVDC projects to be tendered over next one year, which can include projects from Brahmaputra basin, Trombay to inside Mumbai and follow-on orders for existing HVDC projects in Mumbai. Apart from HVDC projects, the visibility on base transmission orders has also started improving, based on the recent projects awarded to key developers as well as CEA recommendations to NCT. We expect one HVDC win for GVTD every alternate year after the recent award and 13% growth in base orders.
Export inflow trajectory to remain mixed
GVTD received export inflows of INR21b/INR33b/INR12b during FY24/25/26, which included few large orders too. This year it expects base export inflows to grow by 10-15% through multiple channels and can potentially get large orders too from the parent entity. It is hopeful of booking one order worth INR13b from a US data center project in FY27 from the parent entity, while the other large export inflow of INR30b is currently delayed.
Capex of INR10b planned across sub-segments
GVTD has planned a capex of INR10b up to Dec’28 across locations
1) to increase transformer and reactor capacity by 50%
2) to add new lines for HVDC valves (LCC) and VSC-STATCOM valves
3) to increase AIS and GIS capacity
4) to set up a new plant for disconnector, GIB components and dead tank assembly. Overall, GVTD expects 40% investment to happen across new areas and 60% across HVDC. The company believes that these investments are sufficient to cater to the existing and upcoming projects.
Financial outlook and valuation
We cut our margin estimates slightly to bake in the impact of current RM prices in FY27/FY28. We expect revenue/EBITDA/PAT CAGR of 26%/24%/24% over FY26-29E. The stock is currently trading at 71x/55x/47x on FY27E/FY28E/FY29E EPS. We maintain BUY rating on the stock with a TP of INR5,100, based on average of DCF and 58x P/E Dec’28E EPS.
Key risks and concerns
Key risks include lower-than-expected growth in base orders, margin pressure, higher competition, and delays in execution ramp-up across HVDC projects.
For More Research Reports : Click Here
For More Motilal Oswal Securities Ltd Disclaimer
http://www.motilaloswal.com/MOSLdisclaimer/disclaimer.html
SEBI Registration number is INH000000412


.jpg)