Real Estate Investment in India: Opportunities, Costs and Risks
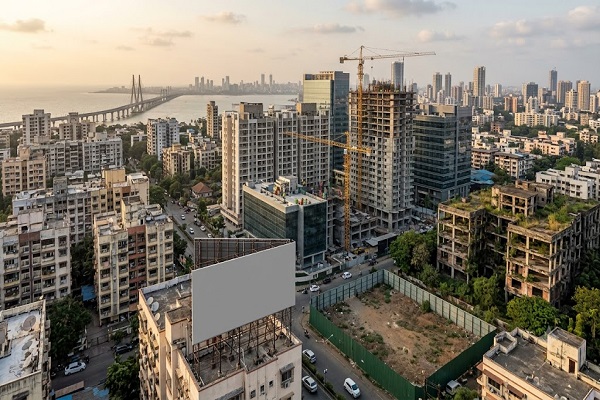
Real estate investment has long been considered an important option for wealth creation in India. From residential apartments and commercial properties to land and rental assets, the sector offers several opportunities for investors seeking long-term capital appreciation and regular income. Growing urbanisation, infrastructure development and demand for housing continue to make property investment an area of interest for individuals and businesses.
However, investing in real estate requires careful financial planning, market research and an understanding of the costs involved. Property prices do not always rise, rental income is not guaranteed, and selling a property can take considerable time. Understanding the opportunities, expenses and risks can help investors make informed decisions.
Understanding Real Estate Investment in India
Real estate investment involves purchasing property or property-related assets with the objective of generating rental income, earning a profit through future price appreciation or diversifying an investment portfolio.
Unlike stocks and mutual funds, physical property generally requires a substantial initial investment and involves legal documentation, maintenance and transaction costs. Investors should therefore evaluate their financial goals, investment horizon and ability to manage unexpected expenses before purchasing a property.
In India, investors can consider several options, depending on their budget, risk tolerance and preferred level of involvement.
Major Real Estate Investment Opportunities
1. Residential Property
Residential properties, including apartments, independent houses and villas, are among the most familiar forms of real estate investment. Investors may purchase a property to rent it out or sell it later if its market value increases.
Demand for housing in growing cities and developing suburban areas can create opportunities for investors. Locations near employment centres, educational institutions, hospitals and public transport may be attractive to prospective tenants.
However, a property's investment potential depends on factors such as purchase price, neighbourhood development, rental demand, maintenance expenses and the availability of competing properties.
2. Commercial Real Estate
Commercial properties include offices, retail shops, warehouses and other spaces used by businesses.
These properties may offer attractive rental opportunities when located in areas with established commercial activity. Long-term leases can also provide relatively predictable rental income when tenants remain financially stable and fulfil their contractual obligations.
Nevertheless, commercial real estate often requires a larger investment than some residential properties. Vacancy periods, changes in business demand and tenant defaults can affect returns. Investors should carefully evaluate the location, lease terms, maintenance responsibilities and financial strength of prospective tenants.
3. Land Investment
Purchasing land is another option for individuals seeking potential long-term capital appreciation. Land located near expanding urban areas or planned infrastructure developments may attract interest from future buyers.
However, land investment requires particular attention to legal ownership, land-use permissions, access roads, zoning restrictions and applicable development regulations. Agricultural land may also be subject to state-specific ownership and transfer rules.
Unlike a rented apartment or commercial unit, vacant land generally does not generate regular rental income unless it is put to a permitted and commercially viable use. Investors may also need to wait several years before finding a suitable buyer.
4. Real Estate Investment Trusts (REITs)
Real Estate Investment Trusts offer an alternative for investors who want exposure to income-generating real estate without purchasing an entire property.
Listed REITs allow eligible investors to buy units through the stock market. These trusts typically hold or invest in income-producing real estate assets, such as office buildings and other commercial properties, subject to their investment structure and applicable regulations.
REITs can provide greater accessibility and liquidity than direct property ownership. However, their unit prices may fluctuate, distributions can vary, and market conditions can affect performance.
Investors should review the REIT's portfolio, financial performance, distribution history, debt levels and regulatory disclosures before investing.
5. Property Investment in Emerging Urban Locations
Infrastructure improvements, new transport links, industrial development and the expansion of employment hubs can influence property demand in developing areas.
Investors may explore residential and commercial opportunities in cities and suburbs experiencing economic growth. However, announced infrastructure projects do not guarantee future price appreciation.
Before investing, buyers should examine whether a project has received the necessary approvals, whether construction is progressing as planned and whether genuine housing or commercial demand exists in the area.
Costs Involved in Real Estate Investment
The purchase price is only one part of the total cost of owning property. Investors should calculate the complete financial commitment before making a decision.
1. Down Payment and Home Loan Costs
Buyers using a home loan generally need to contribute a portion of the purchase price from their own funds. The remaining amount may be financed by a lender, subject to eligibility and lending conditions.
Investors should account for the down payment, loan processing fees, legal charges, applicable insurance costs and interest payments. A larger loan can increase financial pressure, particularly when rental income is insufficient to cover the monthly instalment.
Before borrowing, compare loan offers and calculate whether repayments remain affordable under different interest-rate and income scenarios.
2. Stamp Duty and Registration Charges
Property transactions generally involve stamp duty and registration charges. The applicable rates and rules depend on the state, property type, transaction value and other relevant factors.
These expenses can add significantly to the upfront cost of purchasing property. Buyers should verify the prevailing charges with the relevant state registration department before finalising a transaction.
3. Maintenance and Repair Expenses
Property owners may need to pay for repairs, painting, plumbing, electrical work, society maintenance and other recurring expenses.
Residential properties may also involve society charges and expenses for common facilities. Commercial properties can require additional spending on equipment, building systems and tenant-related modifications.
Setting aside a maintenance reserve can help investors manage unexpected expenses without disrupting their household finances.
4. Property Tax and Insurance
Property owners may be liable for municipal property tax, depending on the applicable local rules. Insurance can also be useful for protecting buildings and certain contents against specified risks.
The amount payable varies according to the property's location, size, assessment and insurance coverage. Investors should include these expenses when estimating annual ownership costs.
5. Taxes and Selling Expenses
Selling a property may involve brokerage fees, documentation expenses and applicable capital gains tax. Tax treatment depends on factors such as the nature of the asset, the holding period, the seller's circumstances and the tax provisions applicable to the transaction.
Investors should review the latest income-tax rules before selling a property or planning tax-related transactions. Professional advice may be helpful when the investment involves substantial gains or multiple properties.
Key Risks of Real Estate Investment
Although real estate can contribute to long-term wealth creation, it is not a risk-free investment.
1. Property Price Fluctuations
Property prices can rise or fall depending on economic conditions, local demand, interest rates, infrastructure development and the supply of new homes or commercial buildings.
An investor who purchases property at an inflated price may experience limited appreciation or financial losses when selling. There is no guarantee that property values will increase every year.
2. Low Rental Yield
Rental yield measures the annual rental income relative to the property's purchase price.
For example, a property purchased for ?60 lakh that generates ?18,000 per month in rent earns ?2.16 lakh annually. This represents a gross rental yield of 3.6% before maintenance, taxes, vacancy and other expenses.
The actual net yield would be lower after deducting ownership costs. Investors should compare expected rental income with the total investment cost rather than relying solely on anticipated price appreciation.
3. Delayed Possession and Project Risks
Investing in an under-construction property may involve construction delays, changes in project specifications or disputes with the developer.
Buyers should verify project registration, approvals, construction progress, payment schedules and contractual terms before committing funds.
The Real Estate (Regulation and Development) Act, 2016 (RERA) establishes a regulatory framework intended to improve transparency and protect homebuyers. Eligible projects must comply with the applicable registration requirements. Buyers can consult the relevant state's RERA portal to review available project information and disclosures.
4. Legal and Title Disputes
Unclear ownership, undisclosed loans or encumbrances, unauthorised construction and land-use violations can create serious legal problems.
Before purchasing a property, investors should have the title documents and ownership history examined by a qualified property lawyer. They should also verify the approved building plans, relevant permissions, applicable land records and any outstanding dues.
A low purchase price should not outweigh concerns about ownership or legal compliance.
5. Liquidity Challenges
Unlike listed shares, physical property cannot always be sold quickly at a desired price. Finding a buyer, completing legal formalities and receiving payment may take time.
This can become a problem for investors who need immediate access to cash or are managing substantial loan repayments.
Investors should therefore maintain adequate emergency savings and avoid committing all their available funds to an illiquid asset.
6. Vacancy and Tenant Risks
Rental income depends on attracting and retaining tenants who pay on time. Extended vacancies, property damage, disagreements and tenant defaults can reduce returns.
A realistic rental estimate should account for possible periods without tenants. Proper tenant verification, a written rental agreement and clear maintenance responsibilities can help reduce avoidable problems.
How to Evaluate a Property Before Investing
A structured evaluation process can help investors identify potential problems before purchasing a property.
Research the location: Examine transport connectivity, employment opportunities, nearby facilities and future development plans.
Compare market prices: Review comparable properties in the same neighbourhood rather than relying only on the seller's quoted price.
Calculate expected returns: Estimate rental income, recurring expenses, financing costs and potential resale expenses.
Verify legal documents: Confirm ownership, approvals, applicable land-use permissions and any recorded encumbrances.
Check developer credibility: For new projects, review the developer's track record, project disclosures and construction progress.
Assess affordability: Ensure the investment does not compromise essential household expenses, emergency savings or other financial commitments.
Consider your exit strategy: Think about how and when you might sell the property if your financial goals or circumstances change.
Is Real Estate a Good Investment for Beginners?
Real estate may suit investors who have sufficient capital, a long-term investment horizon and the ability to manage ownership costs. However, direct property ownership is not necessarily the best starting point for everyone.
Beginners with limited savings may prefer to first establish an emergency fund, manage expensive debt and understand their broader financial goals. Listed REITs may provide a way to explore real estate exposure with a smaller investment, although they carry market risks and are not equivalent to owning a physical property.
The right choice depends on an individual's income, financial obligations, risk tolerance, liquidity needs and investment objectives.
Conclusion
Real estate investment in India offers several potential opportunities, including residential rentals, commercial properties, land and REITs. However, successful investing requires more than identifying a location where property prices might rise.
Buyers must consider the complete cost of ownership, evaluate legal documentation, assess realistic rental returns and prepare for risks such as vacancies, price fluctuations and delayed sales.
A disciplined approach that combines thorough research, careful borrowing and long-term financial planning can help investors make better property decisions. Real estate may form part of a diversified investment portfolio, but returns are never guaranteed, and every investment should be assessed according to the investor's individual financial circumstances.