Quote on FPI Flows in Indian Markets for the week of 26-30 October 2026 by Dheeraj Gaur, Chief Investment Strategy Officer at Choice Wealth
Below the Quote on FPI Flows in Indian Markets: for the week of 26–30 October 2026 by Dheeraj Gaur, Chief Investment Strategy Officer, Choice Wealth
Foreign investors walked back in this week – and the Nifty gave them a warm welcome. Oil, as usual, was the guest nobody invited.
Equity Flows: The FPIs are back (for now)
After roughly nine weeks of selling, FPIs finally turned net buyers. On provisional basis, they sold Rs 1,462 crore on Monday, bought Rs 4,240 crore on Tuesday and Rs 872 crore on Wednesday, sold Rs 944 crore on Thursday and bought Rs 3,599 crore on Friday.Around Rs 6,305 crore of net buyingagainst around Rs 2,700 crore of selling last week and Rs 8,990 crore the week before. DIIs had their lightest week of October, they bought around Rs 3,110 crore. On provisional data, October ended with FPIs at about –Rs 45,160 crore and DIIs at about +Rs 62,220 crore.
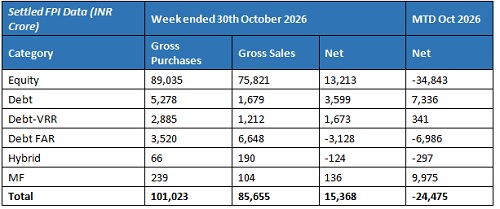
The settled numbers were even stronger. The week’s custodian reports show FPIs as net buyers of about Rs 13,213 crore in equities – roughly Rs 2,272 crore on Monday, a Rs 964 crore outflow on Tuesday, a big Rs 10,584 crore on Wednesday, Rs 2,124 crore on Thursday and a modest Rs 803 crore outflow on Friday. The detail matters: Rs 7,958 crore of that came from the primary market, including Rs 6,386 crore on Wednesday’s report alone, which fits the timing of the Jio Platforms allotment (my reading again). Secondary-market buying was about Rs 5,255 crore.
That changes October’s scorecard. On a settled basis, October ends at about Rs 34,843 crore in the red – much better from the Rs 48,056 crore hole we were in a week ago and now a shade smaller than September’s Rs 35,861 crore. Calendar-2026 outflows stand at roughly rs 2.95 lakh crore.
For the detail-minded:
So, what changed this week?
Quite a lot, actually. The Nifty gained 2.0% to 23,053 – its first close above 23,000 in eight sessions – and the Sensex 1.8% to 74,459. Mid-caps and small-caps rose about 2.2% each, pharma led the board with a gain of about 6%, and the India VIX ended at a calmer 15.28. The Federal Reserve held rates at 3.75–4.00% on Wednesday, and Chair Kevin Warsh’s remarks were read as less hawkish than feared. The US 10-year yield settled back around 5.00%, which gave Asian markets room to breathe.
And then there was Jio. Jio Platforms listed on Wednesday at Rs 1,358, a 21.36% premium to its Rs 1,119 issue price, and closed its first day at Rs 1,419, a market value of about Rs 13 lakh crore. Retail investors did not hang about: Zerodha called Wednesday probably a record day for equity delivery selling. Foreigners, meanwhile, had already done their bit through the allotment.
In short: FPIs came for the new building and also bought a few bricks from the old one too.
Debt Flows: More general, less FAR
Debt was a story of switching lanes. Across the week’s reports, FPIs bought about Rs 3,599 crore through the general limit and Rs 1,673 crore through VRR, but sold about Rs 3,128 crore in FAR. Most of the FAR selling came in one go – rs 2,583 crore on Wednesday’s report – and the route is now down about rs 6,986 crore for October, the weakest line in the table. Put the three together and debt was still a net inflow of about Rs2,140 crore.
Yields helped. The 10-year G-sec touched 7.498% on Tuesday – almost exactly the 7.50% level everyone was watching – and then rallied, ending the week around 7.4%. That is the first weekly gain in bond prices in 11 weeks, ending a record losing run that had added about 70 bps. Mutual funds bought roughly Rs 4,000 crore of bonds, and the Fed’s tone helped. The rupee held at about Rs 95 to the dollar (RBI reference rate Rs 95.37 on Friday versus Rs 94.70 a week ago), with the RBI doing its bit.
Why the cautious optimism?
Same cast, kinder script – except for one.The Fed paused, but a December hike is still priced at roughly 80%, so nobody is celebrating yet. Oil remains the wild card: Brent eased to about $113.70 on Thursday on hopes of peace talks, then jumped to about $117.84 on Friday after a tanker attack near Hormuz. Iran’s answer to a Qatar-mediated proposal is also due around the start of next week. The rupeewas fairly stable and earningshave been supportive. FPIs even bought Rs 3,599 crore on Friday, despite the oil spike, which is the part worth watching.
The catch: one good week after nine not so good ones is not yet a trend and a good part of this week’s settled buying was Jio-shaped.
What to watch next week?
A full five-session week, with a lot of global events packed in. What will matter for FPI flows:
* US midterm elections on Tuesday, 3 November. Fiscal policy, trade and global risk appetite are all in play.
* US jobs report on Friday, 6 November. The consensus is for about 55,000 payrolls after 29,000 in September, with the ADP report and ISM data earlier in the week. With a December hike largely priced in, a strong print could push yields back up.
* Central banks. The RBA (Tuesday) and Bank of England (Thursday) are both expected to hike, a reminder of how global the tightening cycle has become.
* Brent and the Gulf. Does oil continue to boil or cools down or does Iran’s response change the picture?
* The rupee and G-sec yields. Whether the 10-year stays below 7.50% and whether FAR buyers return.
* Q2 earnings. More results and guidance are still to come and the weekly Nifty expiry falls on Tuesday.
Bottom Line:Foreigners turned buyers this week – about Rs 6,305 crore on provisional data and about Rs 13,213 crore on settled data, with Rs 7,958 crore of that coming from the primary market. October closes at about –Rs 34,843 crore on a settled basis, slightly better than September. The real test is whether they keep buying through the US midterms, a jobs report and oil – without a Jio-sized issue doing the heavy lifting.
The views are personal. Data points are referenced from publicly available information, internal sources and other third-party sources believed to be reliable. While every care has been taken to ensure veracity of data, however, the writer cannot guarantee the accuracy of such information
assure its completeness, or warrant that such information will not be changed. The information in this report may include inaccuracies or typographical errors.
Above views are of the author and not of the website kindly read disclaimer