Market Outlook: Key Trends & Actionable Insights September 2026 by PL Wealth Management
Macroeconomic Environment
• Growth: India's Q1 FY27 GDP came in at 7.8% (MoSPI, Aug 31, 2026) — the strongest quarterly print of FY27 so far — driven by robust Investment (+11.9% GFCF) and strong industrial output (Industry +8.6%, Manufacturing +9.2%, Services +10.0%; PIB, Aug 31). The RBI projects FY27 GDP at 6.7% (Q2: 7.0, Q3: 6.5, Q4: 6.8). Non-food bank credit growth accelerated to 19.1% YoY as of July 31, 2026 (RBI fortnightly data, released Aug 31) — capacity utilisation at 75.2% in Q4FY26 (RBI OBICUS) remains above the 74% long-run average, pointing to imminent fresh capacity addition.
• Inflation: July CPI stands at 4.45% (food and beverages: 5.52%; MoSPI, Aug 12, 2026). Core CPI (excl. food and fuel) held steady at 3.9%. WPI Jul came in at 9.78% (DPIIT). The RBI has revised its FY27 CPI projection to 5.0% — with Q3 expected to peak at 5.9%, which PL Research believes is at risk of being breached given El Niño dynamics. Core inflation is projected to align higher by year-end. Brent crude averaged $90–93/bbl in August, closing at ~$93/bbl (Aug 31) — each $10/bbl rise adds ~30bps to headline CPI.
• FCNR & Liquidity: The RBI re-introduced FCNR deposits to stabilise the rupee (down 13% in the 12 months to June 2026) and rebuild reserves. The special window closed August 31 with total mobilisation reaching approximately USD 100bn (ICICI Prudential AMC, Sep 2, 2026) — FCNR(B) deposits alone rose from USD 17.4bn to USD 65.4bn in five weeks. This added 2.5–3% of system deposits in liquidity, easing G-Sec yields and stabilising the rupee. Forex reserves recovered from USD 667bn to USD 717bn (~10.7 months import cover). GST collections: rs 1,99,853 crore gross in August 2026 (+14.8% YoY; GoI, Sep 1, 2026), approaching the Rs 2 lakh crore milestone.
• FPI & DII Flows: FPIs were net buyers of ~USD 3bn in Indian equities in August 2026 (second consecutive month of net buying; NSDL / ICICI Prudential AMC, Aug 28). DIIs continued to provide strong liquidity support, purchasing equities worth ~USD 6bn during the month. The combination of sustained domestic buying and returning FPI confidence provides a meaningful market cushion.
• El Niño & Monsoon Risk: Cumulative monsoon deficit stands at 13% as of August 26 (IMD) with 16–17 meteorological sub-divisions in deficient territory. Kharif sowing is 2% below normal — rice and oilseeds worst hit. Skymet: 70% probability of full-season drought with a 15% deficit. PL Research warns that a strengthening El Niño could trigger a global agricultural commodity spike — Sugar, Palm Oil, Coffee, Cocoa, Soybean — putting RBI's own Q3 CPI peak estimate of 5.9% at risk of overshoot. PL India Strategy explicitly flags 25–50bps rate hike probability in 3Q/4Q FY27, contingent on crude and monsoon trajectory.
Domestic Market Outlook
Momentum returns selectively: FPIs back as buyers for the second consecutive month, Midcap outperformance intact, Q1FY27 earnings broadly ahead of expectations — though elevated crude and El Niño keep the environment cautious.
Q1 FY27 Earnings PL Coverage Universe posted sales/EBITDA/PAT growth of 21.1%/1.7%/3.7% YoY. Ex-Oil & Gas, PAT grew 17% — the strongest since Q4FY24 — with a beat of 2.6% versus PL estimates. The Nifty 500 universe (ex-OMC) grew earnings +23% YoY (Motilal Oswal Research, cited in ICICI Prudential AMC, Sep 2026). The broad-based beat was the standout — Banks, Metals, Telecom and Healthcare all delivered positive surprises. However, PL Research cautions that companies carry 45–60 days of imported raw material stock purchased at elevated prices, and 2Q/3Q margins remain at risk. GFCF rose 11.9% in Q1FY27, corroborating the capex upcycle.
Market Valuation & PL Nifty Targets At 24,208 (Aug 26), Nifty trades at 17.3x one-year forward EPS (FY27E: Rs 1,349) — an 11.7% discount to the 15- year average PE of 19.6x and a 14.8% discount to the 10-year average of 20.3x. PL Research FY28E EPS: Rs 1,537 (+14.0% YoY), 2.5% below Bloomberg consensus (rs 1,576). 12-month base case Nifty target: 27,123 (17.6x × FY28E EPS), implying ~12% upside. India's EM valuation premium to EM at a 10-year low (Morningstar Q3 2026) — a structurally attractive entry point for long-term allocators.
PL Model Portfolio — Sector Positioning PL Model Portfolio: +30.0% vs Nifty since November 2018 inception. OW: Banks (FCNR liquidity boost, EBLR tailwind; OW M&M, Eicher, cut Maruti), Capital Goods/Defence (L&T, BEL, HAL, ABB), Diversified Financials (Bajaj Finance, Shriram Finance), Metals (buying opportunity), Healthcare (adding Aster DM Quality Care, UW Sun Pharma), Telecom (Bharti Airtel), Ports (Adani Port). UW: IT Services (AI disruption uncertainty; reducing Infosys, TCS), Auto (growth moderation), Consumer (+200bps cut), Oil & Gas (Equalweight Reliance, Nestle).
Equity Market — Overview and Strategy
EQUITY MARKET India's market performance showed mid and small-cap resilience while large-cap remained under pressure. FPIs net buyers for two consecutive months. Stock-picking theme intact — sector rotation toward Banks, Cap Goods, Metals, Telecom and away from IT, Consumer, Auto.
Short Term — 0 to 6 Months (Selective / Staggered) Markets remain cautiously constructive. FPIs were net buyers for two consecutive months — +Rs 20,200 Cr in July and ~USD 3bn in August (NSDL / ICICI Prudential AMC, Aug 28, 2026) — alongside DII buying of ~USD 6bn in August, providing a solid domestic liquidity cushion. Nifty trades at 17.3x FY27E PE, an 11.7% discount to the 15-year average, which limits meaningful downside. However, Brent crude at ~$93/bbl (Aug 31) and the El Niño-driven monsoon deficit create near-term overhang on Q2/Q3 margins and rural demand. The PL Model Portfolio remains overweight on quality banks, capital goods and defence, while cutting IT, consumer and auto. A staggered, stock-picking approach in quality large-cap and diversified constructs is preferred over passive index exposure at this juncture. Preferred categories: Quality Large Cap · Large & Mid Cap · Flexi-cap.
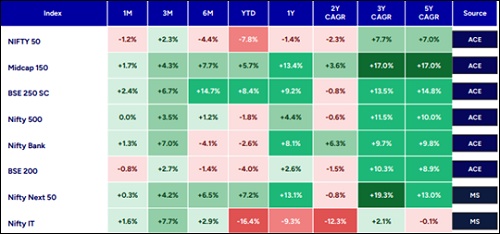
Medium Term — 6 to 24 Months (Constructive / Build) The medium-term opportunity is characterised by three structural tailwinds converging. First, non-food bank credit growth accelerated to 19.1% YoY (Jul 31, RBI), supported by FCNR-driven liquidity of ~USD 100bn — providing growth capital to the economy. Second, the capital expenditure cycle is robust: GFCF grew 11.9% in Q1FY27, with PL overweight on capital goods (Defence, Power, Renewables, Data Centres, Semiconductors). Third, mid and small-cap earnings are growing faster than large-cap — Midcap 150 has delivered +17.0% 5Y CAGR versus Nifty 50 at +7.0% (ACE MF TRI), a 10 percentage point annual alpha gap. PL base target of 27,123 implies ~12% upside. Build core exposure in large private banks (BFSI FY27E EPS +20.2%; PL OW), capital goods and consumer durables. Preferred categories: Large Cap · Large & Mid Cap · Quality Small Cap · Flexicap / Multi Cap.
Long Term — 24 Months+ (Overweight India) The structural India investment case is increasingly validated by earnings. India's EM valuation premium is at a 10-year low (Morningstar Q3 2026). Structural drivers — demographics, financial deepening, defence indigenisation, domestic capex, and Make in India — remain firmly intact. Newer high-growth spaces (EVs, defence, renewables, capital markets, digital) continue to emerge outside large-cap indices, providing the alpha opportunity that PL flags. PL Model Portfolio has outperformed Nifty by 30% since inception (Nov 2018). Preferred categories: Mid Cap · Small Cap · Infra & Defence Thematic · Flexi-cap.
RBI POLICY
Repo Rate: 5.25% · SDF: 5.00% · MSF / Bank Rate: 5.50% · Stance: Neutral · Cumulative easing since Feb 2025: 125bps
Policy Backdrop & Strategy The August 2026 MPC was bond-positive: the RBI upgraded its FY27 GDP forecast to 6.7% and lowered its CPI projection to 5.0%, maintaining a neutral stance for the fourth consecutive meeting. The FCNR window closed August 31 with total mobilisation reaching approximately USD 100bn (ICICI Prudential AMC, Sep 2, 2026), adding 2.5–3% systemic liquidity and anchoring the front end of the yield curve. Bloomberg EM bond index inclusion drives structural FPI demand for FAR G-Secs (15Y, 30Y, 40Y), providing a durable demand floor. However, PL India Strategy explicitly flags a material probability of a 25–50bps RBI rate hike in 3Q or 4Q FY27, contingent on El Niño-driven food inflation and crude prices. This makes outright duration positioning premature. The dominant strategy remains Accrual Over Duration.
Short End 3M–3Y · Overweight Accrual Systemic liquidity surplus from FCNR (~2.5–3% of system deposits) anchors the front end. Certificates of Deposit (CDs) are offering ~7.0–7.5% and Commercial Papers (CPs) ~7.3–7.8% — providing attractive high-accrual with minimal duration risk. With no near-term rate cut expected — and a meaningful probability of a rate hike in H2 FY27 per PL Strategy — the short end is the most efficient expression of fixed income exposure. Morningstar India: Liquid / Overnight funds (6.8–7.0% effective yield), Ultra Short Duration (3–6M Macaulay), Low Duration (6– 12M Macaulay), Money Market. Best risk-adjusted segment for parking and near-term deployment.
Belly 5Y–8Y · Tactical / Overweight The 10-year G-Sec yield settled at ~6.72% post-August MPC. PL Research's fair value range for the 10-year is 6.75–6.90%, with a tactical add recommendation on any yield spike above 6.95%. Bloomberg EM bond inclusion continues to drive structural FPI demand for FAR G-Secs — the belly (5Y–8Y) represents the tactically attractive zone: carry above 6.75% with potential capital gains if crude stabilises. Morningstar India: Short Duration funds (1– 3Y Macaulay), Banking & PSU Debt (AAA/Sovereign only), Corporate Bond funds (AA+ and above; fair value 7.0– 7.2%).
Long End 10Y+ · Neutral / Selective PL India Strategy explicitly flags 25–50bps rate hike risk in H2 FY27 — making outright long-duration positioning premature at current levels. However, Bloomberg EM bond inclusion provides a structural FPI bid for FAR 15Y, 30Y, and 40Y G-Secs, creating a durable demand floor for long-end paper. The appropriate vehicle for longduration exposure is Dynamic Bond funds (active duration management through the rate cycle) rather than fixed Gilt or Constant Maturity products. Add only on 10-year yield spikes above 6.95%. Morningstar India: Gilt funds, Dynamic Bond funds, Medium to Long Duration (3–5 year horizon).
Above views are of the author and not of the website kindly read disclaimer



More News
Daily Update Report 22nd October 2026 by Ventura Securities Ltd