Key Highlights: Stocks in News, Economic & Global Updates 13th November 2026 by GEPL Capital Ltd
Stocks in News
• NBCC: The company signs an MoU with the West Bengal government for various development works in the state.
• AMAGI MEDIA LABS: The company entered into a pact with Golden Times Media Tech to bring Chinese entertainment channels to global platforms.
• CLEAN MAX ENVIRO: The company signed an MoU with the Andhra Pradesh government to invest Rs 50,000 crore in a clean energy complex that will power a 2 GW compute factory.
• ZEE ENTERTAINMENT: The company approved a buyback of up to Rs 600 crore, comprising up to 6.6 crore shares at Rs 91 per share. The buyback represents 7.22% of the company's equity.
• KRISHNA GVK: The company Announced a 256-key luxury hotel in Bengaluru to be operated by Indian Hotels under the Taj brand, with an investment of Rs 500 crore in Taj Yelahanka.
• DYNACONS SYSTEMS: The company received a $6.83 million order from the Ministry of Public Works in Dominica.
• GAIL: The company signed a pact with Krishak Bharati Cooperative for a gasbased fertiliser project and will build a 1.27 MMTPA urea plant in Andhra Pradesh.
• NAVIN FLUORINE: The Company commenced operations at its 15,000 MTPA HFC R32 plant in Surat.
• TVS MOTORS: The company expanded its presence in Mauritius with the launch of two new models.
• EIH: The company will invest Rs 777 crore in a new hotel in Hyderabad, which is expected to become operational by September 2030.
Economic News
• India’s Retail Inflation Hits 6.09%, Breaching RBI’s Upper Tolerance Limit and Fueling December Rate Hike Bets: India’s retail inflation surged to 6.09% in October, breaching the RBI’s 6% upper tolerance limit for the first time under the new CPI series, driven by food inflation rising to 8.94% from 7.74% in September, while core inflation accelerated to 4.5%; widening price pressures have strengthened expectations of a second consecutive 25 bps repo rate hike in December, with inflation potentially remaining above 6% until June 2027.
Global News
• Asian Markets Rebound as Nvidia Uncertainty and Hawkish Fed Bets Keep Investors Cautious: Asian markets edged higher on Friday, with MSCI Asia-Pacific rising 0.26%, South Korea’s Kospi gaining 2.35% and Japan’s Nikkei advancing 1.4%, recovering from a turbulent week amid concerns over Nvidia CEO Jensen Huang’s resignation and its potential impact on the global AI industry and semiconductor supply chain. Nvidia shares fell 3% in extended trading, while investors shifted towards competitors such as AMD, Broadcom and Arista. Meanwhile, hawkish Fed expectations following hotter-thanexpected US inflation pushed the US 2-year Treasury yield to 4.89% and the 10-year yield to 5.14%, lifting the dollar towards a 0.9% weekly gain as markets priced in a 14.5% probability of a jumbo 50 bps rate hike in December. The yen weakened towards 160 per dollar, while Brent and WTI crude eased 0.3% to $95.45 and $88.39 per barrel, respectively, after rising geopolitical tensions and disruptions to Strait of Hormuz shipping.
Government Security Market:
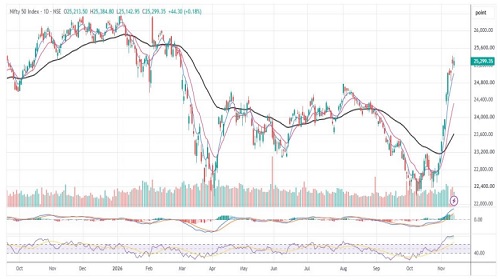
* The Inter-bank call money rate traded in the range of 4.30% - 5.60% on Thursday ended at 5.10% .
* The 10 year benchmark (6.94% GS 2036) closed at 7.2467% on Thursday Vs 7.2139% on Wednesday
Global Debt Market:
U.S. Treasury yields edged higher Thursday as bond trading resumed after the Veterans Day closure and investors looked ahead to fresh inflation and housing data for clues about the economy and the Federal Reserve’s next move. The yield on the 10-year U.S. Treasury note the benchmark for mortgages, auto loans and credit card debt was up 2 basis points at 5.0100%. The 2-year Treasury note yield, which is more sensitive to short-term Federal Reserve interest rate decisions, was 5 basis points higher at 4.7800%. The longer-dated 30-year Treasury note yield which often moves on geopolitical developments was steady at 5.3503%. The rise in yields comes as traders await more domestic data releases this week for fresh insights into the U.S. economic picture. On Friday, the latest monthly producer price inflation print, which tracks wholesale inflation, is expected to show a 0.4% rise in October, down from the 1.3% surge in September. Before that, investors are also looking out for October’s home sales report from the National Association of Realtors, due later Thursday. Existing home sales rose by 1.5% in September to 3.99 million, up from a two-year low the previous month, and are expected to reach 4 million last month, according to Trading Economics estimates. Oil prices were broadly flat in early trading, as Middle East negotiations remain deadlocked. U.S. West Texas Intermediate futures were up less than 0.1% at $86.59 a barrel, while Brent crude rose 0.17% to $92.92.
10 Year Benchmark Technical View :
The 10 year Benchmark (6.94% GS 2036) yield likely to move in the range of 7.2250% to 7.25% level on Friday
SEBI Registration number is INH000000081.
Please refer disclaimer at https://geplcapital.com/term-disclaimerg