Energy Market Report: Rising supply surplus weighs on oil price momentum by Emkay Global Financial Services
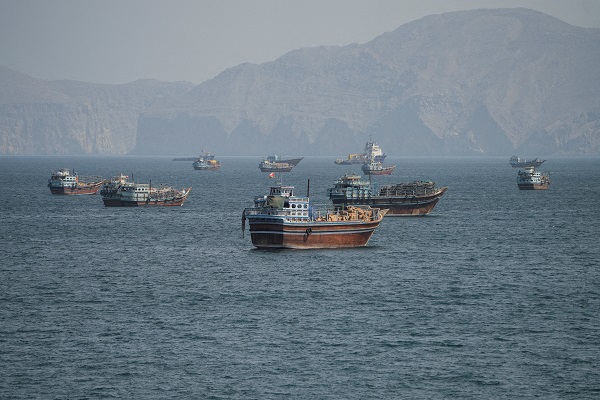
Crude oil recorded a second consecutive weekly decline as improving Persian Gulf export flows and expectations of a softer global supply-demand balance outweighed persistent geopolitical and shipping-related risks surrounding the Strait of Hormuz. NYMEX WTI crude oil declined 2.56% to settle at $88.56/bbl, witnessing a wide intraweek trading range of $83.88–$91.42/bbl. The inability to sustain gains above the $90/bbl psychological threshold highlights the presence of substantial overhead supply and reflects weakening bullish momentum. Domestic markets broadly mirrored international weakness, although the decline was relatively contained amid currencyrelated dynamics. MCX crude oil fell 1.08% to close at Rs8,369/bbl, after testing an intraweek low of Rs7,861/bbl.
Fundamentally, the outlook for crude oil has become increasingly challenging, with the International Energy Agency (IEA) projecting a global supply surplus of approximately 2mn barrels per day during the current quarter. The gradual normalization of seaborne exports from the Persian Gulf has improved physical availability, prompting Asian refiners to increase purchases of Middle Eastern crude grades and reduce their reliance on alternative long-haul supplies, particularly from the United States. Consequently, a significant portion of the geopolitical risk premium accumulated during October has been unwound from crude oil prices. While persistent uncertainties surrounding the Strait of Hormuz continue to provide some downside protection, the absence of further material supply disruptions is likely to limit the scope for a sustained geopolitical premium.
Demand-side indicators are also signaling a softer consumption environment across major economies. China's crude oil imports declined approximately 15% yoy to 9.9mn barrels per day in October, reflecting subdued refining activity and a relatively weak domestic economic environment. Meanwhile, European diesel consumption has experienced double-digit yoy declines amid persistent industrial weakness, while US gasoline demand remained below prior-year levels during the peak summer driving season. Collectively, these indicators reinforce concerns regarding the sustainability of global oil demand growth and increase the likelihood of a more comfortable supplydemand balance
On the policy front, the US administration's decision to extend the Jones Act waiver by 90 days is expected to provide additional flexibility to domestic energy logistics. The extension allows energy companies and commodity traders to continue using foreignflagged vessels for coastwise shipments between US ports, helping alleviate maritime transportation bottlenecks and contain domestic fuel costs. Improved vessel availability and reduced freight constraints could ease regional supply-chain pressures, providing an additional moderating influence on domestic energy prices and refined product differentials.
We expect WTI to remain range-bound with a negative bias, and rallies toward immediate resistance levels are likely to encounter selling pressure. A sustained recovery above the $93.50/bbl would be necessary to improve the near-term technical outlook.
In contrast to crude oil, natural gas demonstrated strong bullish momentum, registering a decisive weekly recovery across international and domestic exchanges. NYMEX natural gas advanced 7.18% to settle at $3.230/mmbtu, after touching an intraweek high of $3.397/mmbtu. Domestic prices followed suit, with MCX natural gas gaining 7.92% to close at Rs308/mmbtu. The sharp advance indicates improving buying interest and a potential shift in short-term market momentum, although the sustainability of the breakout will depend on the ability of prices to overcome key technical resistance levels.
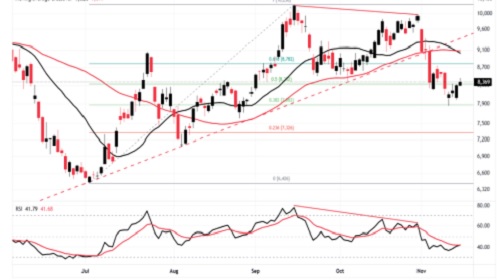
MCX Crude Oil Technical Outlook
* MCX crude oil future’s last three sessions price action formed a sequence resembling a basebuilding reversal.
* The fast black moving average (9,026) has crossed below the slower red moving average (9,079), confirming a recent bearish crossover overhead.
* The 14-period RSI reading 41.79 (signal line at 41.68), curling slightly upward from sub-40 territory. Momentum remains bearish-to-neutral.
MCX Natural Gas Technical Outlook
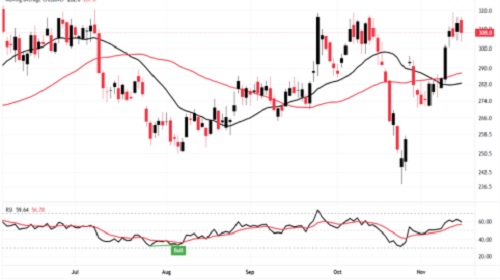
* MCX natural gas staged an aggressive V-shaped recovery in early November, surging back above the moving averages into the 320.0 major resistance zone, this forms a classic rejection pattern at horizontal resistance.
* Price is trading well above both the fast black moving average (282.6) and the slow red moving average (287.6).
* The RSI reading 59.64 (above its signal line at 56.78), reflecting healthy bullish momentum. However, it is flattening slightly in line with the price rejection at resistance.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH000000354