Commodity Weekly Report – 27th September 2026 by Choice Broking
Gold
COMEX Gold closed around $4,284/oz, declining 2.13% for the week, pressured by a stronger dollar, elevated US Treasury yields and rising expectations of further Fed rate hikes. Markets price a nearly 70% chance of an October hike, supported by resilient US economic activity and jobless claims. COMEX speculative net longs fell 5,727 contracts to 131,334 for the week ended September 22. Meanwhile, unresolved US-Iran talks supported oil prices and geopolitical concerns. However, In India, gold demand improved modestly as lower prices attracted festive-season buying. Focus this week will remain on US jobs data, ISM PMIS, PCE inflation, ECB signals and China's PMIs.
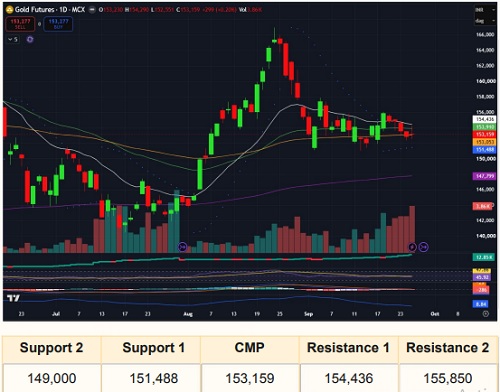
MCX Gold December contract has been traded negatively over the course of the week, declined by -1.75% in past week and managed to settle at 153,159. Price has posted a lower low closing for past five consecutive sessions and remained below 20 and 50-DEMA levels placed at 154,436 and 153.910 respectively. Daily SAR is placed at 151,488 which will be crucial support to look for. Major support would be at 200-DEMA level placed at 147,799 and breakout below this mark will bring more downside momentum shift in Gold price for Long term. Looking at Ol levels in next expiry, we can observe a rise in Ol levels to 12,850 lots with price decline, suggesting Short buildup. RSI levels remained around 45-50 on Daily and Weekly timeframe.
The overall trend in Gold price is expected to be Sideways-to Bearish in the coming week, and traders should keep an eye on key US economic data such as Final GDP, PCE Price index, Manufacturing PMI along with employment data such as Avg. hourly earnings, NFP, Unemployment rate and Unemployment claims, which are scheduled to be in next week.
Silver
COMEX Silver prices closed around $64/oz, down nearly 3% for the week, pressured by rising US Treasury yields and expectations of further Federal Reserve rate hikes. Stronger-than-expected US economic data, including September PMI figures showing the fastest business activity growth in five years, reinforced expectations for tighter monetary policy. Markets are pricing a 66% probability of an October hike according to CME FedWatch. The US 10-year Treasury yield remained near 5.2%, close to multi-year highs, while elevated inflation expectations and worsening fiscal conditions continued to weigh on bonds and precious metals. Meanwhile, uncertainty surrounding US-Iran negotiations and potential disruptions to Strait of Hormuz flows kept energy prices volatile. The University of Michigan survey showed consumer sentiment falling to a four-month low, while inflation expectations remained elevated, reinforcing pressure on silver.
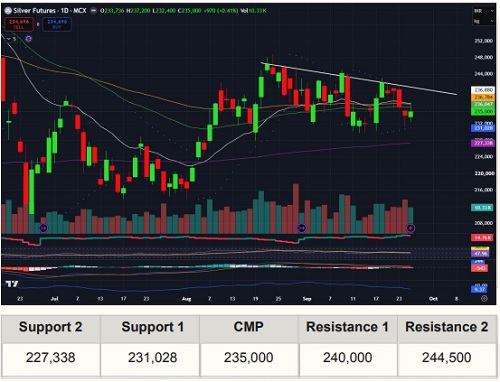
Silver future has continued its downward spiral after a pause of previous week, declined by -2.89% and closed at 235,000. After marking a support low of 231,293 on Thursday, Silver price has rebounded significantly on Friday, showing signs of recovery. However, price has still remained in a bearish bias for short term, settled in past week below 20 and 50-DEMA levels 236,880 and 236,047 respectively. Immediate support would be at Daily SAR level placed at 231,028 and breakout below this mark will boost downward momentum in Silver. Major support is marked at 200-DEMA level placed at 227,338.
We are expecting Sideways-to-Bearish trend in Silver in the upcoming week and traders should look for Sell-on-rise opportunity.
Crude Oil
WTI Crude Oil eased to around $92/bbl, with prices remaining volatile amid shifting expectations over US-Iran diplomatic efforts and Middle East supply flows. Iran proposed reopening the Strait of Hormuz and resuming nuclear talks within seven days if the US lifts its naval blockade, unfreezes Iranian assets and ends military operations. However, President Trump rejected the proposal, saying the US controls the waterway and that oil flows remain substantial. Despite recent gains, WTI declined around 4% for the week. CFTC data showed speculative net longs in WTI rising by 8,952 contracts to 148,467 for the week ended September 22. Going forward, markets will closely monitor US-Iran negotiations, potential escalation involving GCC states, Hormuz disruptions, Middle East supply recovery and US diesel export policies.
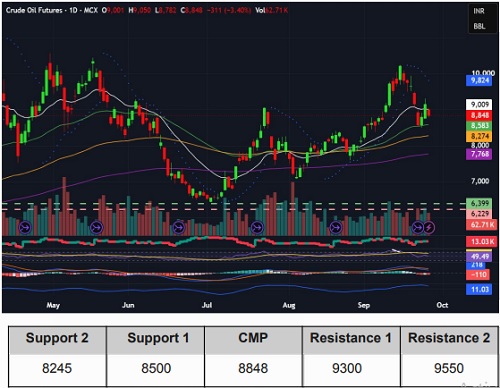
MCX Crude Oil prices witnessed volatility during the week amid geopolitical developments, closing at 8848 while sustaining above the key 20-50-100-200 DEMA placed at 8786, 8251, 7814 and 7140, respectively, indicating that the broader trend remains supportive. Prices are finding support around the 8500 level, while Ol has gradually increased to 13,030 lots, suggesting rising market participation. The price structure continues to indicate moderate bullish momentum, although volatility and geopolitical developments may influence near-term movements.
Overall, the trend remains moderately bullish, with traders advised to monitor the support aphe, ande V closely track geopolitical news and developments. A sustained move above recent highs couldting strengthen bullish momentum
Natural Gas
US Natural Gas prices fell below $3.15/MMBtu on Friday as traders booked profits after prices reached a 13-week high following supply disruptions in West Virginia. TC Energy's Columbia Gas Transmission declared force majeure after a mechanical issue, triggering a sharp price rally. Despite the correction, prices gained around 10% for the week, supported by stronger LNG feedgas demand, with September flows averaging 17.8 bcfd versus 17.2 bcfd in August. EIA data showed a 53 Bcf storage build for the week ended September 18, narrowing the surplus above the five-year average. Weather forecasts indicate mostly normal conditions through early October. In Europe, storage above 70% remains below seasonal norms, while Norwegian maintenance is restricting pipeline supplies, keeping the market vulnerable to disruptions.
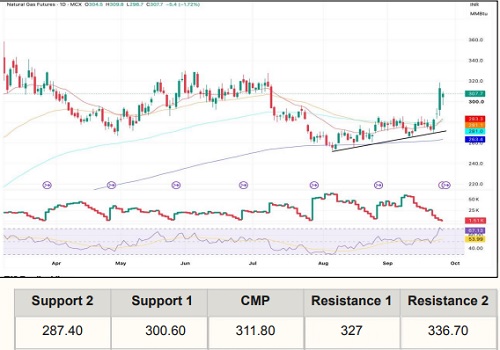
MCX Natural Gas prices witnessed a sharp recovery, gaining over 10% during the week, with the September contract made a high of 318.50 and closing at 307.70. Meanwhile, the October contract closed at 311.80, sustaining above the key 20-50 DEMA placed at 299.10 and 297.30, respectively, indicating improving short-term momentum. The rise in Open Interest alongside the price rally suggests fresh participation in the market, supporting the ongoing bullish structure. The RSI is placed at 61.07, above its average of 52.23, reflecting positive momentum.
Overall, the trend remains moderately bullish, with prices showing improving strength. Traders should closely monitor the key support zone and consider short-term corrections as potential opportunities for a buy-on-dips approach, while keeping an eye on volatility and further price action.
Copper
LME Copper futures ended the week higher, supported by mounting supply disruptions and robust demand linked to global electrification. Operations at BHP's Escondida mine in Chile, were suspended, with no timeline for restart. Supply pressures are further intensifying as several Chinese smelters schedule maintenance for early Q4, pushing the LME copper prompt spread to its highest level this month. Meanwhile, stronger-than-expected US manufacturing activity in September indicated resilient demand. Longer-term consumption remains supported by expanding electrification projects, including US data centres and Chinese energy-storage infrastructure. Peru expects to add around 1 million tonnes of annual copper production over the next 5-6 years. CFTC data showed COMEX copper speculative net longs rising 17,108 contracts to 82,649.
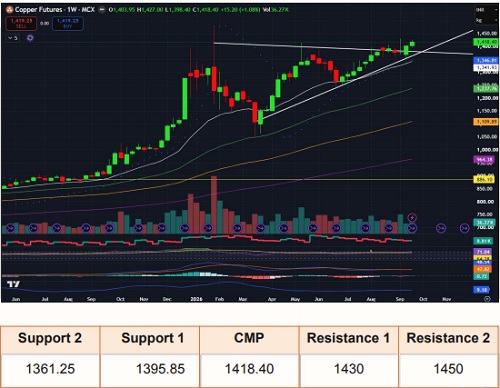
Copper price made an another attempt to breakthrough the hurdle of Ascending triangle formation and continued to trade positively for 2nd consecutive week, inclined by +1% and managed to close at 1418.40. Price has settled above its all key moving averages ie. 20. 50 and 100-DEMA levels placed at 1395, 1373 and 1340 respectively. Daily SAR is also placed at 1361,25 which will be a major support level to look for. On the opposite side, crucial resistance would be at 1430 and breakout above this mark will boost upward momentum in Copper price towards 1450. The momentum indicator, RSI remained elevated over 60-70 level on Daily, Weekly as well as Monthly charts.
We are expecting continuation of Bullish momentum in Copper price in next week and traders should look for Buy-on-dips opportunity.
Aluminium
LME Aluminium prices fell as prospects of improving supply and a stronger US dollar weighed on prices. Several smelters are restarting previously idled capacity, while others are advancing expansion plans. Rising Chinese exports are also offsetting part of the supply disruptions from the Gulf, with aluminium exports increasing 17.2% year-on-year in August amid subdued domestic demand and elevated inventories. China also exported 425,003 tonnes of alumina in August, up 136% year-on-year, with 54% shipped to Russia. Meanwhile, hawkish Fed comments strengthened the dollar, adding pressure to dollar-denominated metals. Trump's rejection of Iran's Hormuz reopening proposal could add further uncertainty over regional supply flows.
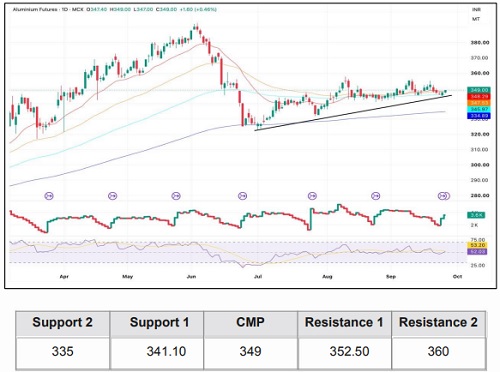
MCX Aluminium prices continued to witness a sideways movement during the week, closing at 349 while sustaining above the key 20-50-100-200 DEMA placed at 348.29, 347.53, 345.10 and 334.89, respectively, indicating a supportive broader trend. The prices are consolidating near the recent highs, with the rising trendline providing additional support. Open Interest has increased to 3,600 lots, suggesting fresh market participation. The RSI is placed at 53.20. marginally above its average of 52.03, reflecting a neutral-to-positive momentum setup.
Overall, the trend remains sideways to moderately bullish. A sustained breakout above the recent high could strengthen bullish momentum and support further upside. Traders should closely monitor the breakout levels and key moving averages for confirmation of the next directional move.
For Detailed Report With Disclaimer Visit. https://choicebroking.in/disclaimer
SEBI Registration no.: INZ 000160131


Tag News
Weekly Commodity Insights 28th September 2026 by Axis Securities Ltd