Buy Tata Consultancy Services Ltd For Target Rs.2,530 By Geojit Financial Services Ltd
AI Push Strengthens Growth Visibility
Tata Consultancy Services (TCS), a subsidiary of Tata Sons Ltd, is a global IT company providing services to the banking, financial services and insurance - BFSI; telecommunication; transportation; retail and manufacturing sectors
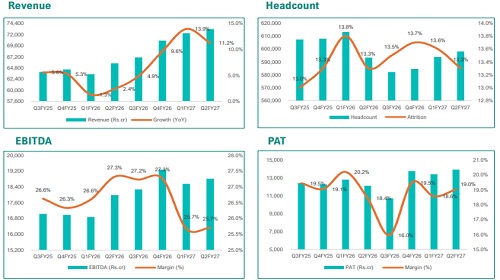
* Consolidated revenue rose 11.2% YoY to Rs. 73,188cr in Q2FY27 owing to growth in the international market; better performance in BFSI, manufacturing and tech; artificial intelligence -AI revenue exceeding $3.1bn; and major deal wins.
* Europe revenue rose 12.0% YoY to Rs. 24,155cr on the back of strong growth in the UK, which reported 4.5% YoY constant-currency growth during Q2FY27.
* EBITDA rose 4.7% YoY to Rs. 18,815cr, while EBITDA margin contracted 160bps to 25.7%, due to higher other operating expenses (+35.0% YoY) and cost of equipment and software licences (+39.8% YoY).
* Adjusted profit after tax rose 5.1% YoY to Rs. 13,884cr on robust growth in global markets and strong profitability despite higher cost pressures.
Outlook & Valuation
TCS delivered a steady quarter, supported by broad-based growth across international markets, continued client expansion and a robust pipeline of transformation-led engagements across key geographies and industry verticals. Strategic partnerships with Porsche AG, Best Buy, Aareal Bank and Dubai Gold & Commodities Exchange, along with the proposed acquisition of MHP Management-und IT-Beratung GmbH (MHP), should strengthen its capabilities across AI, cloud, digital transformation, infrastructure services and automotive consulting. Continued AI-led momentum and investments in talent, delivery and industry solutions should enhance long-term growth visibility and competitive positioning. While we modestly recalibrate FY27E/FY28E EBITDA margins by 110bps/100bps to reflect higher subcontracting costs, growth investments and the expected ~50bps dilution from MHP, these initiatives should strengthen execution capabilities and support future growth opportunities
We retain our BUY rating on the stock, with a revised target price of Rs.2,530 based on 16x FY28E adjusted EPS.
Key Concall Highlights
* Demand remained resilient in Q2FY27, with total contract value -TCV at $9.6bn and broad-based client expansion. The number of clients contributing $10mn, $5mn and $1mn in revenue increased by 2, 6 and 11 from the previous quarter, respectively.
* Porsche signed a five-year strategic agreement with TCS, providing long-term revenue visibility and strengthening the IT major’s presence in the global automotive technology and AI services market.
* Best Buy’s global capability centre in India will transition to TCS and be transformed into an AI capability centre.
* TCS announced the proposed acquisition of MHP Management-und IT-Beratung GmbH (MHP), Porsche AG’s automotive and industrial consulting subsidiary, for an enterprise value of €320mn.
* The strategic partnership with Aareal Bank positions TCS to provide end-to-end infrastructure support, cloud operations, workplace services and cybersecurity, supporting long-term digital transformation and technology modernisation objectives.
* Dubai Gold & Commodities Exchange partnered with TCS to modernise its market infrastructure through a next-generation integrated trading, clearing and surveillance platform, supporting future growth and operational efficiency.
* Headcount of TCS increased to 598,056 in Q2FY27 from 593,798 in Q1FY27, while voluntary LTM attrition in IT services fell 30bps to 13.3%, reflecting steady workforce expansion and better retention.
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH200000345