Buy Sun Pharmaceutical Industries Ltd For Target Rs.2,070 By Geojit Financial Services Ltd
Strengthening Specialty-Led Growth Momentum
Sun Pharmaceutical is India’s largest pharmaceutical company and a leading global specialty generics company. It develops, manufactures and markets branded and generic formulations, and active pharmaceutical ingredients.
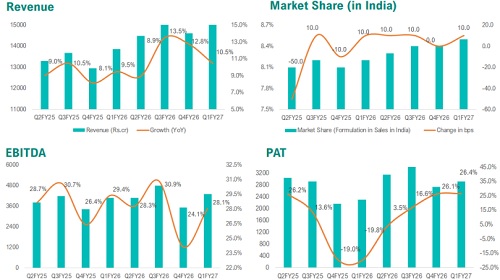
* In Q1FY27, consolidated revenue from operations rose 10.5% YoY to Rs. 15,300cr, on strong growth in the India formulations business and sustained momentum in the Innovative Medicines portfolio. The company expects high single digit growth in the business this year led by speciality and domestic segments.
* The Global Specialty business (22% of sales) delivered broad-based growth, led by strong performance from ILUMYA and ODOMZO, while recent launches such as Leqselvi and Unloxcyt continue to gain traction, supporting growth prospects.
* Sun Pharma continued to strengthen its leadership position in the Indian pharmaceutical market (8.4% Market share), with growth largely driven by volumes and new product launches.
* EBITDA increased 5.5% YoY to Rs. 4296cr, while EBITDA margin moderated to 28.1%, primarily reflecting the absence of the one-off uplift from Lenalidomide sales seen in Q1FY26.
Outlook and Valuation
Sun Pharmaceutical continues to strengthen its position globally through the growing contribution of the Innovative Medicines portfolio and its sustained leadership position in the domestic market. The company has also maintained strong traction in key geographies, including market share gains in India, and continued expansion of its specialty portfolio. The recent approval of semaglutide in multiple markets, steady performance of its flagship brands such as Ilumya and progress in the commercialisation of new specialty products highlight its focus on innovation-led growth. The proposed Organon acquisition is expected to broaden its therapeutic presence through the Women's Health and Biosimilars portfolios while further enhancing its global reach. Hence, we retain our BUY rating on the stock, with a revised target price of Rs. 2,070, based on 30x FY28E adj. EPS.
Key concall highlights
* The $11.75bn Organon acquisition is progressing as planned, with key approvals received and closure targeted by Q4FY27. This is likely to strengthen Sun Pharma’s global scale and expand its Women’s Health and Biosimilars portfolios.
* In Q1FY27, the company invested Rs. 826cr in research and development, representing 5.4% of sales, with a continued focus on innovative therapies and complex product development. * Sun Pharma received investment-grade credit ratings from Moody’s (Baa1/Stable) and S&P (BBB+/Stable), which should improve funding flexibility and support efficient financing of the proposed Organon & Co. acquisition.
* The company incurred Rs. 167cr of Organon-related transaction costs in Q1FY27, comprising due diligence, legal, filing and other acquisition-related expenses.
* Management highlighted semaglutide as a key growth driver, a differentiated auto-injector platform, in-house manufacturing capabilities and expansion into emerging markets such as South Africa and Brazil.
* The company also expanded its generics pipeline in the US, with 558 approved ANDAs and 119 pending filings, including 28 tentative approvals; it filed three ANDAs and secured approvals for six during the quarter
For More Geojit Financial Services Ltd Disclaimer https://www.geojit.com/disclaimer
SEBI Registration Number: INH200000345