Buy MTAR Technologies Ltd For Target Rs.7,090 by ARETE Securities Ltd

MTAR's 2QFY27 revenue grew 200% YoY (+13% QoQ) to Rs 4,068mn (est Rs 3,692mn), driven by the Clean Energy- Fuel Cell, Hydel & Others segment (+243% YoY to Rs 3,339mn), while Aerospace & Defence (+164% YoY), Products & Others (+42% YoY) and Civil Nuclear (+8% YoY) also supported overall growth. EBITDA rose 483% YoY to Rs 992mn (est Rs 886mn) and EBITDA margin expanded 1,184bps YoY (+80bps QoQ) to 24.4% (est 24.0%), supported by operating leverage and better scale utilization. PAT came in at Rs 598mn (est Rs 484mn) against Rs 46mn in 2QFY26. 1HFY27 revenue grew 163% YoY to Rs 7,675mn with EBITDA margin of 24.0%. Management maintained FY27 guidance of ~80% revenue growth with 24% EBITDA margin and expects H2FY27 to be stronger than H1FY27. Order book stood at ~Rs 59,800mn (vs Rs 51,434mn in 1QFY27 and Rs 25,820mn in 4QFY26) on order additions of Rs 12,072mn in the quarter, dominated by clean energy (~82%), followed by Products & Others (~11%) and Aerospace & Defence (~7%). Management is targeting working capital of ~100 days for FY27, aided by customer advances and better payment terms.
Management Call Highlights
• FY27E guidance: revenue growth +80% YoY, EBITDA margin 24% but expects to do better on both revenue and margin; H2FY27 stronger than H1FY27
• Order book ~Rs 5,983cr (vs Rs 5,143cr in 1QFY27); 2QFY27 order additions of Rs 1,207cr. Clean energy is ~82% of the order book
• Record H1FY27 order inflow of Rs 4,102cr; management expects to sustain the momentum and a strong closing order book at FY27-end. Demand for hotboxes exceeds capacity
• Working capital at 50 days in Sep-26 (172 in Mar-26); H1FY27 operating cash flow Rs 350cr; GST refunds of Rs 70-80cr p.a. expected
• Segment reclassification: ~Rs 60cr of box-build revenue (and ~Rs 60cr of order inflow) was booked under clean energy instead of Products & Others; Products & Others revenue was ~Rs 125cr (vs Rs 65cr shown). Company to re-upload the investor deck
• Phase 2 hotbox capacity expansion (~30% above existing capacity) will be operational by end-November 2026; Phase 3 (multifold capacity, new dedicated facility) will be completed by June 2028
• Total capex ~Rs 500cr (~Rs 100cr incurred in FY26, ~Rs 400cr in FY27): Rs 350cr for fuel cell and Rs 150cr for other verticals; 75% through debt and 25% through internal accruals. Rs 50- 100cr annual maintenance/growth capex
• Expect ramp-up in volumes in MNC aerospace (Rs 150cr+ revenue targeted in FY27). First-article qualification for a key customer this year, with long-term-agreement volumes from FY28
• Data centre infrastructure: first article orders of ~Rs 45cr; Phase 1 facility ready by December and Phase 2 by June 2027. Customer has indicated ~8x the first-article requirement, i.e. Rs 350-450cr potential over the next two years
• ROCE ~23% in FY27 (17.2% in FY26), Rs 107 cr net debt after investment
• Majority revenues will be in FY28 and FY29 for nuclear. 2 years for the current orderbook execution
• Mahi Banswara order-Rs 700-1000cr potential
• Product and others- Exports of ballscrews commenced. Rs 500cr revenue guidance. 1-year orderbook for products and orders.
Valuation and Outlook
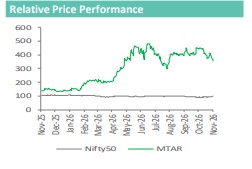
We maintain a BUY rating on MTAR Technologies with a target price of Rs 7,090, valuing the company at 50x September 2028E EPS of Rs 141.8, which is 17.1% above the current market price of Rs 6,057. Our valuation reflects strong earnings visibility from its established Bloom Energy relationship, a robust order book and growing exposure to the SOFC and AI data-centre power opportunity. We estimate revenue/EBITDA to grow at a CAGR of ~71%/~91% over FY26-FY28E, with EBITDA margin expanding from 23.2% in FY27E to 24.5% in FY28E on operating leverage and capacity ramp-up. We use a moderated 50x multiple to allow for valuation normalisation as the AI-led opportunity gets priced in, despite the scarcity premium. Key triggers are the ramp-up of hotbox capacity, rising Bloom Energy deployments and execution of nuclear and aerospace & defence programmes. Key risks are elevated valuations, customer concentration with Bloom Energy (~60% of revenue), execution of the planned capex and working capital requirements.
Please refer disclaimer at http://www.aretesecurities.com/
SEBI Regn. No.: INM0000127