Buy Hindustan Aeronautics Ltd for the Target Rs 5,950 by Emkay Global Financial Services Ltd
Hindustan Aeronautics (HAL) reported revenue of Rs76.1bn (+14.9% yoy), above our estimate of Rs70.6bn. EBITDA at Rs17.4bn (+11.6% yoy) was in line with our estimate of Rs16.7bn. EBITDA margin stood at 22.8% (-70bps yoy; est 23.7%). PAT came in at Rs18.4bn (+10.6% yoy; est Rs17.1bn). We remain confident about HAL’s business prospects, as India is in the midst of modernizing its armed forces due to (1) equipment obsolescence and (2) the prevailing adverse geopolitical situation, driving strong orders for fighter aircraft and helicopters, along with their respective engines and accessories. We expect HAL to deliver strong operational performance over FY26–29E, supported by a pickup in the execution of its Tejas Mk-1A order. We retain BUY with an unchanged TP of Rs5,950, valuing the stock at 32x 1HFY29E earnings.
A good quarter
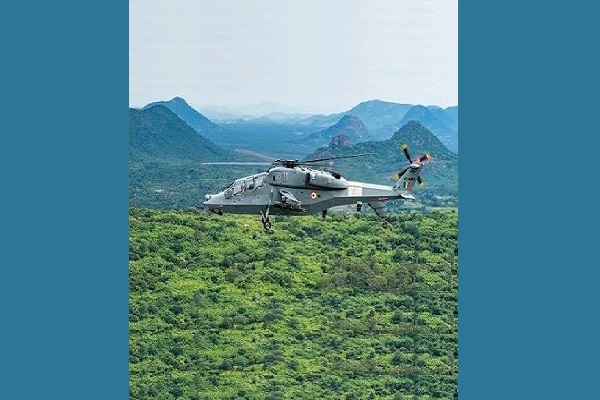
HAL reported revenue of Rs76.1bn (+14.9% yoy), above our estimate of Rs70.6bn. Revenue growth was driven by the delivery of two Tejas FOC Trainers, three HTT-40 Trainers, and four ALH Dhruv NG Helicopters. The management remains confident of healthy revenue growth, with deliveries of LCA Mk-1A expected to commence in 2HFY27. EBITDA stood at Rs17.4bn (+11.6% yoy; est Rs16.7bn), with a margin of 22.8% (-70bps yoy; est 23.7%). Margins contracted as manufacturing revenue contributed +40% during the quarter (historically 25-30%). Going forward, higher deliveries are expected to drive operating leverage and support healthy operating margins. PAT stood at Rs18.4bn (+10.6% yoy), above our estimate of Rs17.1bn.
Update on LCA Mk-1A Delivery Timeline
HAL has indicated steady progress on the LCA Mk-1A program, with 27 airframes ready. GE has supplied 14 engines to date and expects to deliver another four by end-CY26. HAL remains engaged with the Indian Air Force to accelerate handovers and has reiterated its confidence in executing deliveries through 2HFY27.
Robust order book; pipeline looks equally promising
HAL's order book stood at ~Rs2.55trn at the end of FY26. The incremental order pipeline also looks promising, with anticipated contracts for Do-228 (10 units), 43 ALH Dhruv, and 60 utility helicopters for the Navy. The estimated value of the order pipeline stands at Rs1.0trn and is expected to materialize over the next few years. We expect an addressable pipeline of Rs4.5trn over the next 4-5 years.
Investment summary
We believe HAL, with its long-term business outlook and strong execution capabilities, is well positioned to deliver 12% revenue CAGR over FY26–29E. Given its potential for multi-year double-digit earnings growth and a robust return ratio profile of +20%, we believe the stock is attractively valued. We retain BUY with an unchanged TP of Rs5,950, valuing the stock at 32x 1HFY29E earnings.
For More Emkay Global Financial Services Ltd Disclaimer http://www.emkayglobal.com/Uploads/disclaimer.pdf & SEBI Registration number is INH0000003