Buy Elecon Engineering Company Ltd for the Target Rs 679 by Sushil Finance
Elecon Engineering Ltd. recently announced its performance for the quarter ended September 30, 2026. Following are the key highlights.
Highlights from the Quarter (Q2 FY27)
Elecon Engineering Ltd. consolidated revenue reached Rs.638.9 cr, a healthy 10.5% YoY growth over Q2 FY26 numbers. Despite a spike in input costs and logistics due to geopolitical tensions, EBITDA remained resilient at Rs.148 cr with a 23% margin. The consolidated open order book strengthened significantly, rising 33% YoY to Rs. 1,635 cr. Domestically, the demand environment is likely to see improvement post Diwali based on the current pipeline. On exports, the company has started getting good references in cement, steel, and power industries in the US; a healthy order from data centers is expected to open up larger opportunities. The Middle East is showing great momentum, especially Africa and the northern part. The abnormal steel price rise seen in Q1, driven by capacity and supply chain constraints, did not recur in Q2; the market has normalized and so it expects the margins to be better going forward.
Gear Division Performance::
Revenue Rs.488 cr, +10.6% YoY, with overseas market growing by 30.3% yoy. EBIT margins expansion by 290 bps yoy to 22.1% came from the price hikes and higher share of the export orders. Overseas business is increasingly moving from standard gearboxes toward applicationengineered and condition-monitoring solutions, with good traction from data center cooling tower applications and oil & gas applications. Management flagged huge demand coming in from heavy-duty, large-size steel gearboxes, and noted great potential in coal and thermal power for new gearbox applications.
Material Handling Equipment (MHE) Division Performance:
Revenue Rs.151 cr, 10% YoY, as execution improved compared to Q1. Management noted great prospects for MHE exports, with large inquiries coming in from abroad for material handling business.
On the defence front, the management expects the RFP for the gears (P-17 Bravo) submission to be in Q2 or Q3 of FY28, with orders awarded in Q1 FY29. P17 Bravo is a follow-on order to P-17 Alpha, and Elecon expects to be the single bidder, meaning the order goes to Elecon only.
Outlook:
Improvement in the growth is expected, with 15% yoy growth in H2FY27, while margins to remain constant in FY27 as compared to FY26. For FY30, topline is expected to reach ~Rs.5,000 cr, 2x of the revenue in FY26
OUTLOOK & VALUATION
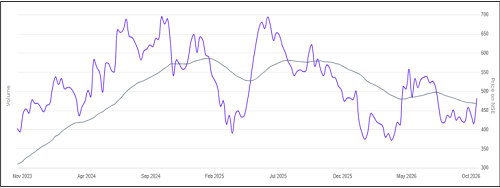
We expect the company’s bottomline to grow at a CAGR of ~16% to Rs. 462 cr in FY26-28E. We view Elecon as a structurally strong play on India’s industrial capex and exports theme, with strong financial health and execution capabilities. The investment thesis rests on: (1) sustained growth driven by infrastructure-led demand, (2) margin stability due to operational excellence, (3) potential upside from export penetration by tie up with OEMs. We have assigned a P/E multiple of 33X to arrive at a price target of Rs. 679 which provides an upside of ~39% within 18 to 24 months from the current market price.
Please refer disclaimer at https://www.sushilfinance.com/Disclamier/disclaimer
Member : BSE/ NSE/ MSEI. SEBI Registration No.-INZ000165135.