Bank Credit Growth Rises to 19.5%, 268 bps Above Deposit Growth by CareEdge Ratings
Synopsis
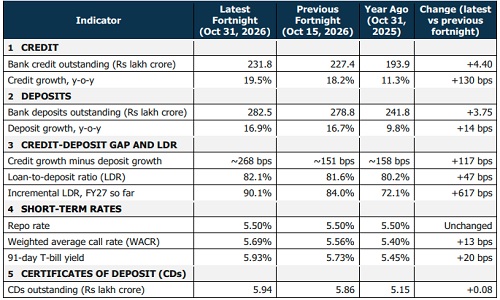
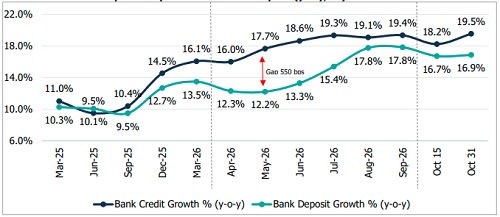
• Bank credit growth rose to 19.5% y-o-y in the fortnight ended October 31, 2026, from 18.2% on October 15. Credit outstanding rose by Rs 4.40 lakh crore to Rs 231.8 lakh crore.
• Credit had fallen Rs 2.52 lakh crore in the previous fortnight, so this rise more than made up for it. Over the two fortnights since September 30, credit is up Rs 1.88 lakh crore, or 0.8%.
• Deposits rose by Rs 3.75 lakh crore to Rs 282.5 lakh crore, and y-o-y deposit growth edged up to 16.9% from 16.7%. Deposits are still Rs 1.45 lakh crore below their September 30 level.
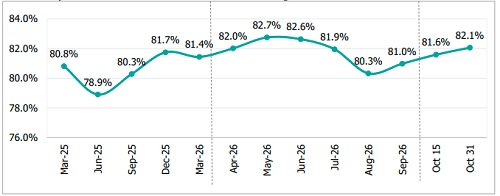
• Y-o-y bank credit growth now exceeds deposit growth by about 268 basis points (bps), up from about 151 bps at October 15. The loan-to-deposit ratio (LDR) rose to 82.1% from 81.6%.
• The weighted average call rate rose 13 bps to 5.69% in the week ended October 30. It is now 19 bps above the 5.50% repo rate.
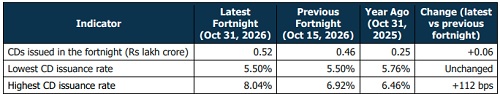
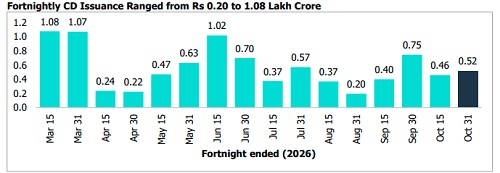
• Banks issued Rs 0.52 lakh crore of certificates of deposit (CDs) in the fortnight, against Rs 0.46 lakh crore in the previous one. The highest CD issuance rate rose to 8.04% from 6.92% a fortnight earlier.
• Part of the high credit growth reflects a low base, as credit grew 11.3% a year earlier. CareEdge Ratings retains its FY27 bank credit growth forecast of 15.0%-16.0%.
Numbers at a Glance
Bank Credit Rises Rs 4.40 Lakh Crore, Reversing the Mid-October Fall
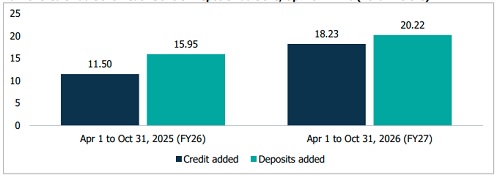
Credit rose 1.9%, or Rs 4.40 lakh crore, in the fortnight. That more than made up for the Rs 2.52 lakh crore fall in the previous fortnight and left credit up Rs 1.88 lakh crore, or 0.8%, since September 30. Y-o-y credit growth of 19.5% is up from 18.2% on October 15 and well above the 11.3% a year earlier. Part of the high growth reflects the low base. Over two years, credit is up 33.0%, or about 15.3% a year. Non-food credit accounted for Rs 4.17 lakh crore of the rise for the fortnight. Credit added in FY27 so far is Rs 18.23 lakh crore, against Rs 11.50 lakh crore in the same period last year. Retail loans (auto, gold, consumer durables, personal) and corporate working capital typically pick up in October and November. With Diwali on November 8, part of that demand should show in the next fortnight. However, the base becomes less favourable in H2FY27. The 25-bps repo rate increase on October 7 will feed into lending rates, first on external benchmark-linked loans and later on MCLR-linked loans as funding costs rise. A rise of this size on its own is unlikely to slow credit demand by much. A sustained increase in lending rates, however, could start to weigh on demand. CareEdge Ratings retains its FY27 bank credit growth forecast of 15.0%-16.0%.
Bank Deposits Rise Rs 3.75 Lakh Crore but Stay Below the End-September Level
Deposits rose 1.3% in the fortnight and recovered part of the Rs 5.19 lakh crore fall after the previous quarterend. Time deposits rose by Rs 1.97 lakh crore, about 53% of the increase, and demand deposits by Rs 1.78 lakh crore. Y-o-Y deposit growth is 16.9%, slightly up from 16.7% on October 15 and well above the 9.8% a year earlier, which was also a low base. Over two years, deposits are up 28.4%, or about 13.3% a year. Over the two fortnights since September 30, however, deposits are down Rs 1.45 lakh crore, against a Rs 1.88 lakh crore rise in credit. Deposits added in FY27 so far total Rs 20.22 lakh crore, against Rs 15.95 lakh crore in the same period last year.
Credit Growth Has Outpaced Deposit Growth Since Sep-25 (y-o-y, %)
Gap Between Credit and Deposit Growth Widens to 268 bps
The gap between y-o-y credit and deposit growth widened sharply in the fortnight, to about 268 bps from about 151 bps on October 15, as credit grew faster than deposits. Credit rose 1.9% in the fortnight while deposits rose 1.3%, so the LDR rose by 47 bps to 82.1%, its fourth consecutive increase and close to the May 2026 peak of 82.7%. The incremental LDR for FY27 rose to 90.1% from 84.0% on October 15, meaning banks have lent out Rs 90 of every Rs 100 of deposits added since April 1. With the repo rate at 5.50% and the liquidity surplus narrowing, funding further loan growth is likely to cost banks more.
Banks' Credit Additions Reach 90% of Deposit Additions, Up From 72% (Rs lakh crore)
Loan-to-Deposit Ratio Rises to 82.1% From 80.3% in August
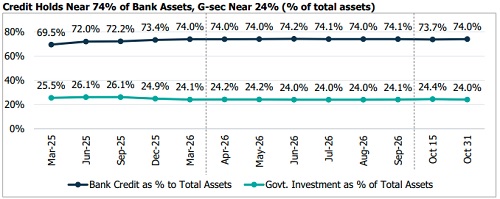
Credit Share of Bank Assets Rises to 74.0% as G-sec Share Eases to 24.0%
Bank credit's share of total assets rose to 74.0% from 73.7% on October 15, while the share of government securities eased to 24.0% from 24.4%. Investments fell by Rs 0.11 lakh crore even as credit rose by Rs 4.40 lakh crore, and the investment-deposit ratio fell to 26.7% from 27.0%.
Call Rate Rises 13 bps to 5.69%, 19 bps Above the Repo Rate
The call rate rose to 5.69% in the week ended October 30 from 5.56% two weeks earlier and is now 19 bps above the 5.50% repo rate, after being 6 bps above it in mid-October. Over the same two weeks, the 91-day T-bill yield rose to 5.93% from 5.73% and the 10-year G-sec yield to 7.45% from 7.40%. The daily minimum CRR, raised to 99% of the required CRR from 90% with effect from the fortnight beginning October 16, has kept overnight rates firm. The liquidity surplus has also continued to narrow: the RBI's net absorption was Rs 1.63 lakh crore on October 31, against Rs 1.86 lakh crore on October 15 and Rs 4.86 lakh crore on September 30. The overnight MCLR range moved up to 7.85%-8.00% from 7.80%-8.00% two weeks earlier, while term deposit rates for tenors above one year were unchanged at 6.00%-6.75%. CPI inflation rose to 6.1% y-o-y in October from 5.5% in September, above the upper end of the RBI's tolerance band, adding to the case for funding costs to remain firm.
CD Issuance Rises 12.7% to Rs 0.52 Lakh Crore
Banks issued Rs 0.52 lakh crore of CDs in the fortnight, up 12.7% from Rs 0.46 lakh crore in the previous fortnight. CDs outstanding rose by Rs 0.08 lakh crore to Rs 5.94 lakh crore. The lower end of CD rates was unchanged at 5.50%, while the upper end rose to 8.04% from 6.92% a fortnight earlier, it’s highest since March 2026, widening the spread to 254 bps from 142 bps. The wider range points to a higher cost of wholesale funds for banks bridging the gap between credit and deposit growth.
Above views are of the author and not of the website kindly read disclaimer