Hold Zen Technologies Ltd For Target Rs.1,612 by ARETE Securities Ltd
Zen Technologies reported a strong 2QFY27, with revenue doubling to Rs 3,451 mn (+99% YoY, +144% QoQ) and EBITDA rising 104% YoY to Rs 1,320 mn, ahead of our estimates by 11% and 29% respectively. EBITDA margin expanded 95 bps YoY to 38.2%, and PAT of Rs 899 mn (+52% YoY) was 20% above our estimate. The order book rose 104% YoY to Rs 13,757 mn on inflows of Rs 4,818 mn. However, management has stepped back from its order-book and revenue targets, counter-drone tenders are yet to be floated and the working-capital cycle has stretched to 379 days.
Management Call Highlights
• The order book is Rs 13,757 mn (equipment about Rs 9,940 mn, AMC Rs 3,807 mn), up from Rs 12,392 mn. Inflow of Rs 4,818 mn exceeded the Rs 3,451 mn executed.
• The working-capital cycle stretched to 379 days from 255 at end-1Q, from higher debtors and supplier advances. 1H operating cash flow was negative. The company is debt-free with about Rs 9,680 mn of cash and bank balances.
• FY27 revenue of Rs 12,000-13,000 mn. Rs 4,850 mn is done, so the rest comes in 3Q and 4Q.
• Long-term margin guidance is about 35%, varying with the antidrone versus simulator mix.
• The CMD walked back earlier targets. He is "not very sure at all" the order book reaches Rs 25,000-30,000 mn by March 2027, and he said it is hard to predict turnover for the next 1-2 years. The Rs 40,000 mn two-year figure assumed orders arrived on time.
• Capacity could handle about double the current order size, and the execution cycle is 12-18 months.
• Fast-track procurement approvals are done and RFPs are expected in weeks to a couple of months. Orders come in 4Q at the earliest, with possible spillover into 1Q or 2QFY28 but historically not beyond 2Q. The capital-acquisition route takes 2-3 years.
• About Rs 4,000 mn+ of simulator orders are expected, but timing keeps slipping. Counter-UAS tenders aren't floated yet, so there are no orders, and the CMD expects most new orders to be counter-UAS.
• Zen bids for about 70-80% of the addressable counter-UAS market and skips the low end. Radar (including AESA) and command and control are fully in-house.
• On exports, Middle East talks have produced no orders. US traction is possible next year, and Europe (SAFE procurement needs 65% local content) could develop early next year.
• HyperStrike is in internal trials. The first order is expected in FY28 and the ramp in FY29. Capacity is 15,000 units a month, starting at about 600 a month.
• R&D was about 12% of revenue in FY26 and expected to be similar in FY27. Over 235 patents are filed, and Cogknit (AI command and control) is expected to contribute meaningfully in about 5 years.
• Capex is about Rs 1,500 mn in FY27 and FY28.
Valuation and Outlook
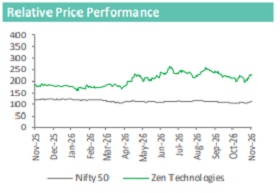
Zen Technologies' in?house product development and IP ownership provide a competitive advantage in customised simulation and counter?drone solutions. The four?layer Vyomkavach system, deployed during Operation Sindoor, positions the company to benefit from the growing demand for counter?drone solutions. However, the near?term growth outlook remains dependent on fresh order awards, particularly as counter?UAS tenders are yet to be floated and management has moderated its earlier order book and revenue targets. We estimate FY26?29E revenue, EBITDA and PAT CAGRs of 49%, 48% and 38%, respectively, with EBITDA margins stabilising at 35%. We value Zen at 30x December 2028E EPS of Rs 53.7, arriving at a target price of Rs 1,612. At the CMP of Rs 1,744, the stock trades at 35.4x FY28E earnings, implying a downside of 8% to our target price. While the long?term opportunity remains attractive, execution visibility and the timing of fresh order inflows remain key monitorables. We downgrade to HOLD, with faster counter?drone order awards, export wins and an accelerated HyperStrike ramp?up acting as potential upside triggers.
Please refer disclaimer at http://www.aretesecurities.com/
SEBI Regn. No.: INM0000127